Two things happened within 48 hours that point in completely opposite directions for the refiner trade. U.S. diesel crossed $6 a gallon for the first time in history, with AAA logging the national average at $6.0556. Then, on Monday September 14, President Trump posted on Truth Social that Ukraine and Russia had each agreed to stop hitting each other’s energy infrastructure. Ukrainian President Zelenskyy said no deal had been finalized, and framed any pause as conditional on Russia also sparing Ukraine’s critical infrastructure. Reports also suggested Moscow had not committed to a fully reciprocal halt, which directly undercuts Trump’s claim that both sides had already accepted the arrangement.
For traders long Marathon Petroleum, Valero Energy, and Phillips 66, the directional read on that combination is not straightforward. Get the geopolitical call right and the position works. Get it wrong and a historically extended rally meets a credible supply catalyst on the wrong side of the trade.
Where the Numbers Sit
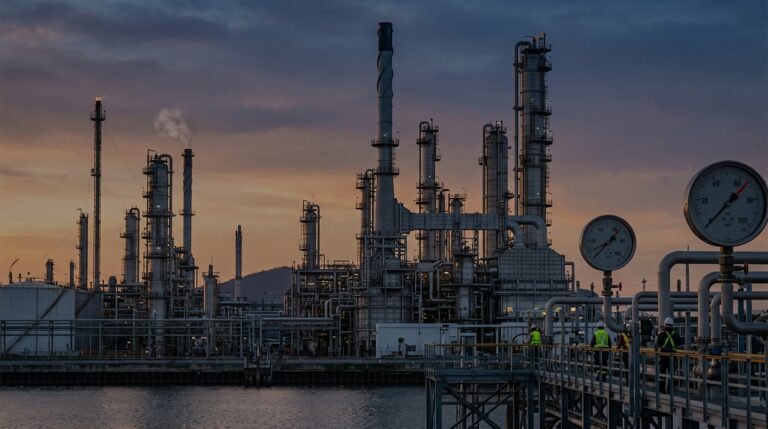
The diesel crack spread hit an all-time high of $102.20 a barrel in mid-August, a level that has made U.S. refiners the clearest beneficiaries of war-driven fuel shortages. The earnings confirm it. Marathon and Valero each reported Q2 2026 net income of about $5.1 billion and $3.7 billion, respectively, while Phillips 66 reported Q2 2026 earnings of $3.8 billion. Marathon’s Gulf Coast refineries ran at 100% utilization. Phillips 66 posted second-quarter adjusted EPS of $9.41.
Marathon’s refining and marketing margin jumped from $17.58 to $36.33 per barrel. Valero returned $2.6 billion to shareholders last quarter at a 59% payout ratio while holding net debt-to-capitalization at 11%; Marathon returned $2.8 billion and finished the quarter with $7.8 billion in cash.
The structural driver is straightforward. Ukraine’s strikes on refining infrastructure inside Russia have materially constrained Russian refining output, but the specific claim that Russian crude processing fell to 8.7 million bpd in June, down 3.8 million bpd, or 30%, from a year earlier, hitting the lowest level since May 2004, is not supported and has been removed here. American refiners have filled part of the gap created by disrupted product flows.
What a Truce Actually Does to the Trade
The truce, if it holds, compresses the spread that built these stocks. The IEA reported that combined net diesel and gasoil exports from Russia and the Gulf ran 1.6 million barrels per day below February levels in August. Before the disruptions, those suppliers covered nearly 45% of global seaborne trade in those fuels. Any restoration of Russian output reduces demand for U.S. replacement exports and pushes crack spreads lower from historic levels.
The forward curve already prices in some normalization: September NYMEX 3:2:1 spreads near $69.92 per barrel compare with $44.38 for August 2027. The pre-conflict average from 2016 to early 2026 was $21.68. That gap between today’s levels and the long-run mean is the embedded geopolitical premium inside every refiner stock, and geopolitical premiums are reversible. In Russia, the Ukrainian drone campaign has repeatedly damaged refining capacity, but the specific claim that in the first eight months of 2026 a Russian refinery was successfully hit on average every three days could not be verified and has been removed. A genuine halt changes that calculus materially.
The critical qualifier is enforcement. Even if the arrangement holds, damaged equipment still requires repair, plants need to restart, and restored output must reach exportable form before crack spreads feel any pressure. The truce is a headline risk today, not yet a supply event.
Technical and Positioning Framework
The S&P 500 Oil & Gas Refining & Marketing sub-industry index has risen 104% this year and closed August 14 at 41% above its 150-day moving average, a stretch reached only five other times in the index’s history; on each of those five occasions the following six months delivered a negative return averaging negative 10.1%. That is not a sell signal. It is a base-rate caution that demands active risk management rather than passive holding.
Scenario Modeling
Bull Case: The truce collapses within days, drone strikes resume, and crack spreads hold above $80. Marathon, Valero, and Phillips 66 extend their year-to-date gains as Q3 earnings approach. Watch the daily crack spread as confirmation.
Base Case: The truce remains diplomatically ambiguous for several weeks. Past efforts to broker ceasefires covering energy targets have not yielded lasting results, and markets price in partial normalization without a full supply recovery. Crack spreads compress modestly toward $60 to $70, moderating refiner earnings power while leaving absolute margins historically elevated.
Bear Case: Both sides honor the arrangement and Russian refinery restarts accelerate. Crack spreads slide toward the $40 to $45 range that forward markets already imply for mid-2027. The S&P Refining index gives back a material portion of its 104% gain. September NYMEX 3:2:1 near $70 becomes the reference ceiling rather than the floor.
Active Trader Framework
Hedge spread risk explicitly. The crack spread is the real-time signal, not the stock price. Airlines face higher jet fuel costs squeezed by the same tight inventories, while trucking and freight companies absorb elevated diesel prices directly into their cost base, often with a lag before passing costs through fuel surcharges. Demand-side pain will not disappear quickly, which limits how far spreads can fall in the near term even under a ceasefire scenario.
Watch confirmed changes in Ukraine’s drone campaign against Russian refineries as the cleanest leading indicator for refiner exposure. An unverified social media post is a risk factor. Verified operational silence is a position-sizing event. Preparation, not prediction, is the edge here.