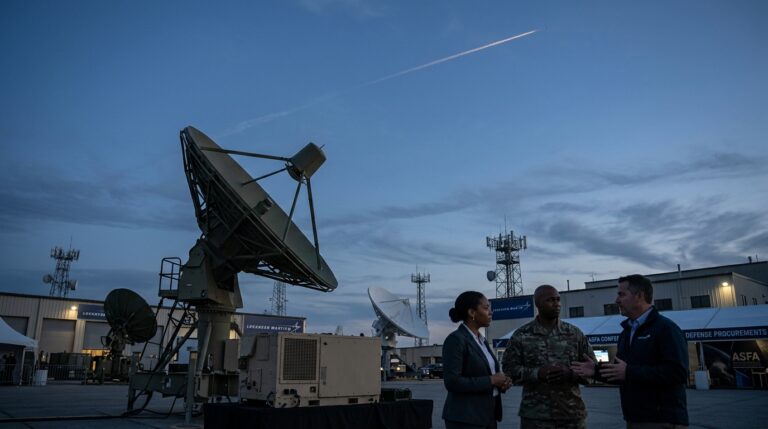
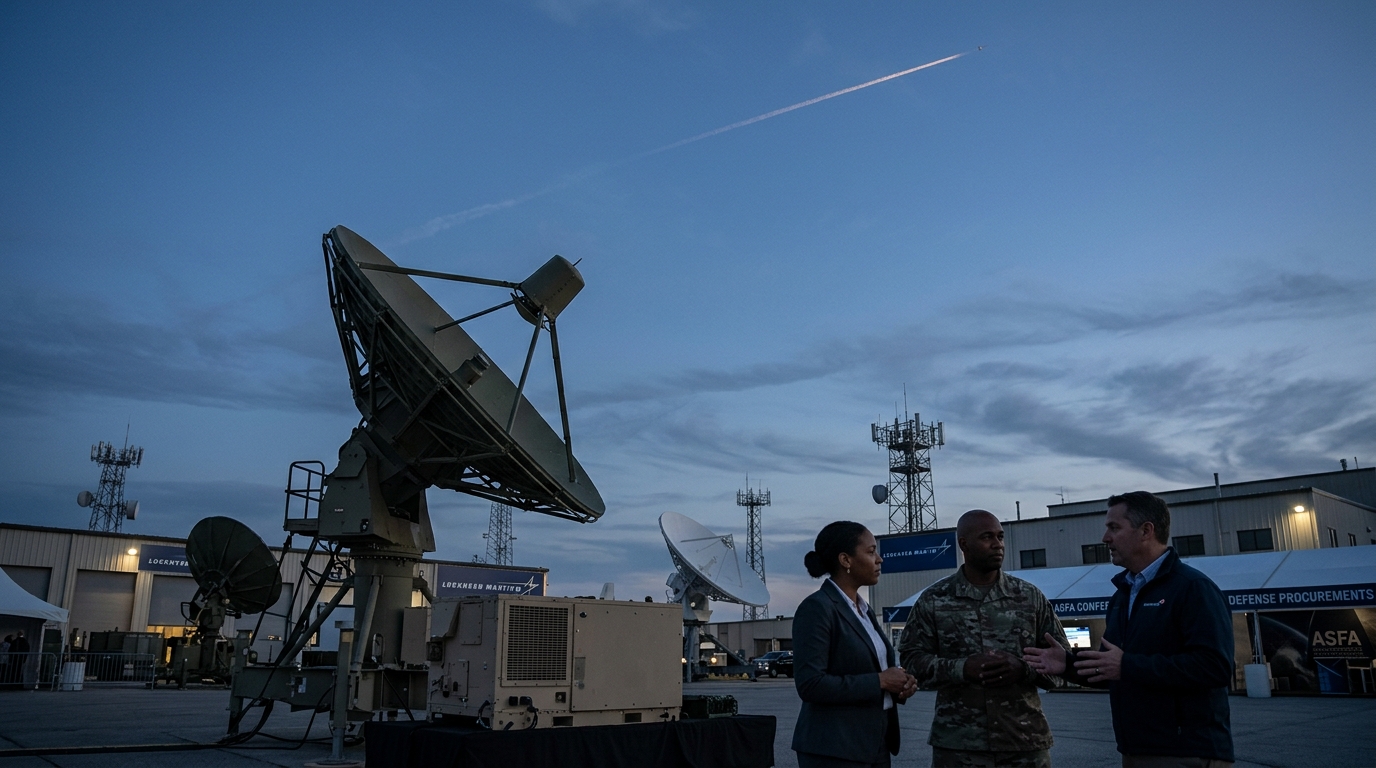
For decades, Pentagon officials described U.S. space activity in terms of ambiguous “capabilities.” That language ended Monday morning in a single sentence. Speaking at the Air and Space Forces Association’s Air, Space and Cyber Conference in National Harbor, Maryland, Secretary of the Air Force Troy Meink broke a decades-old silence: “This is why the United States now has on-orbit space control weapons capable of defending the joint force against hostile adversary action.” In the question-and-answer session afterward, he confirmed the acknowledgment was deliberate and the phrasing “very well thought out.”
The confirmation formalizes what Space Force officials had been hinting at for years as the Pentagon shifted from silence on orbital warfare to open discussion of defensive countermeasures, on-orbit combat, and ground-based satellite-disabling capabilities. The investment committee question is not whether to believe Meink. It is which budget lines this unlocks.
Why Institutional Investors Care
Classified programmes do not appear in analyst models. When the government publicly acknowledges a capability, it signals that associated procurement can move from black-budget obscurity toward open appropriations. The practical logic behind the disclosure is that deterrence only works if an adversary knows a capability exists, and the U.S. has spent years watching Chinese and Russian satellites carry out close-approach manoeuvres. That framing, made public at a major industry conference rather than in a classified briefing, is the Pentagon telling contractors and legislators alike that counterspace spending is entering a new visibility window.
Two Space Force efforts sit inside the broader Golden Dome architecture: the Space-Based Interceptor, which is intended to demonstrate capability integrated into the Golden Dome architecture by 2028, and the Space-Based Air Moving Target Indication constellation, for which SpaceX won a $4.16 billion contract in May 2026. The SBI programme alone is the kind of new spending line that reshapes a sub-sector.
The Bull Case
The disclosure lands against a budget already moving in one direction. The administration’s FY26 national defense budget request was about $1.01 trillion, and the FY26 national defense baseline is roughly $895 billion. Space control is now an acknowledged, publicly-named mission area inside that broader spending complex, which means appropriators have a mandate to fund it openly. For the prime contractors, the question is who already has the programme relationships.
The core prime contractors, including Lockheed Martin (LMT), RTX (RTX), Northrop Grumman (NOC), and L3Harris (LHX), anchor major programmes in missile defence and military satellites. L3Harris is focused specifically on missile-tracking satellites, infrared sensors, communications, and propulsion, positioning it squarely inside the counterspace mission the Space Force just named in public.
The Bear Case
Defence multiples already price in a lot of good news. The FY26 baseline national defense budget is around $895 billion, and that backdrop has pushed Lockheed Martin and peers to premium forward multiples that price in a lot of good news. Meink’s speech does not guarantee contract awards; the appropriations process remains slow and opaque, and large-scale counterspace programmes carry real cost and schedule risk.
Meink declined to describe the type, number, or when the on-orbit weapons were launched, which means programme-level identification remains guesswork. Any contract tied to currently classified systems may not become visible in earnings for quarters or years.
What Investors Are Missing
The most underappreciated name in this discussion is Booz Allen Hamilton (BAH). While investors focus on the hardware primes, the systems engineering and integration work that makes space control weapons operationally effective is advisory and software-intensive. In May 2026, Booz Allen said it was awarded an Other Transaction Authority agreement by U.S. Space Force Space Systems Command as part of Golden Dome for America’s Space-Based Interceptor programme, with the award focused on development and delivery of a prototype system for space-based missile defence. That is precisely the workflow that accelerates when classified programmes surface into open budget lines.
Stocks to Watch
Northrop Grumman (NOC) carries deep space and missile-defence DNA. NOC has been the weakest performer of the prime trio, down 12% year-to-date, but Q1 2026 saw it post EPS of $6.14, while net earnings rose from $481 million to $875 million year-over-year. A re-rating tied to named counterspace programmes would close that gap quickly.
L3Harris (LHX) is the most direct beneficiary of any orbit-tracking expansion. L3Harris has described its Hypersonic and Ballistic Tracking Space Sensor satellite as the only proven on-orbit system capable of tracking advanced hypersonic missiles, and it is positioned to benefit from Golden Dome-related funding and its propulsion businesses.
Booz Allen Hamilton (BAH) is the systems-integration play the ETF flows will miss. Its Golden Dome SBI contract, open counterspace hiring, and classified programme depth make it the hidden beneficiary of budget declassification.
XAR and ITA offer the basket approach for investors who do not want single-programme exposure. ITA is the largest ETF focused on defence, with about $13.3 billion in net assets as of September 2026, and both funds moved on the Meink headline Tuesday. XAR places a large focus on small-cap and mid-cap growth stocks in the defence industry, which results in more volatility but gives the fund a higher ceiling for long-term performance as new programme awards reach smaller contractors.