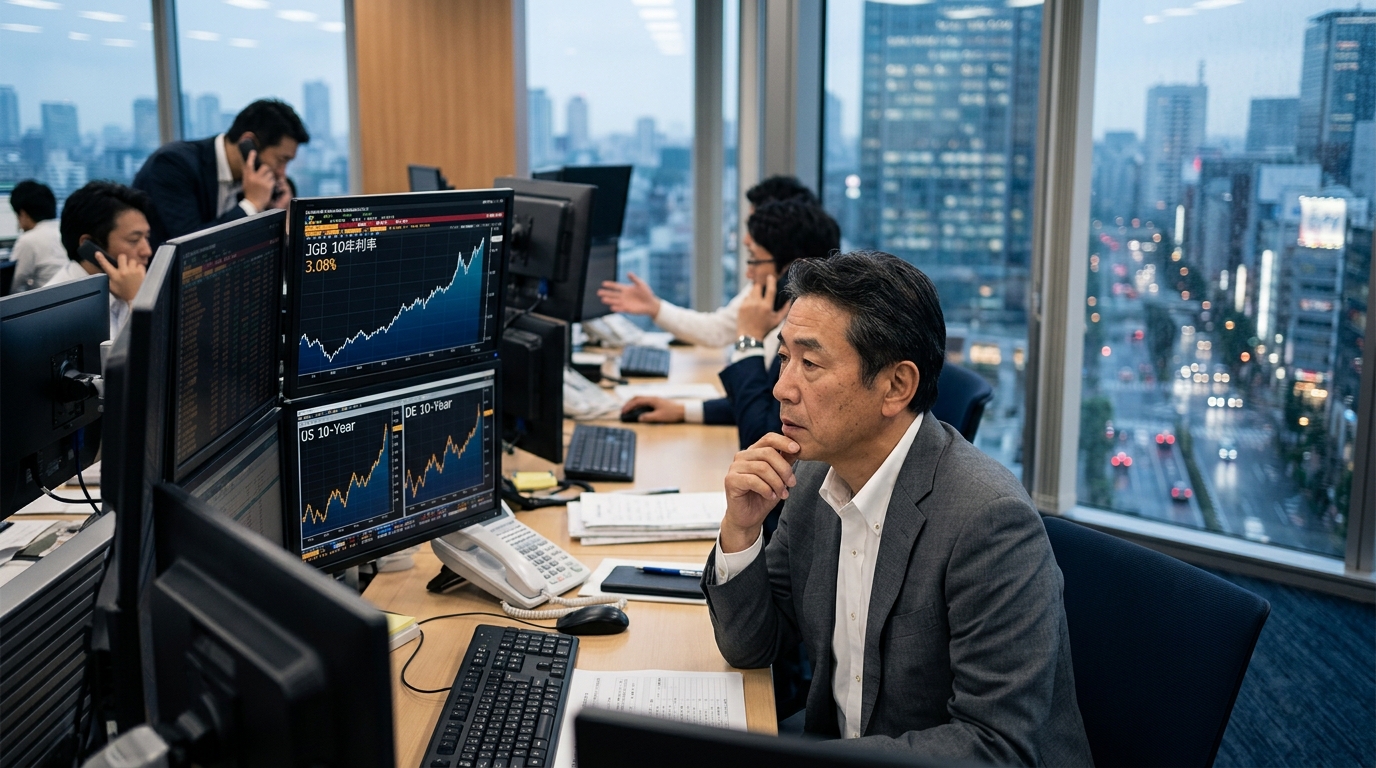
The headline most traders read this week placed the US 30-year yield front and center. That framing misses the point. Japan’s 10-year government bond yield climbed to around 3.08% on Thursday, reaching its highest level since August 1996, tracking a surge in US Treasury yields as strong US private-sector activity data reinforced expectations for further Federal Reserve rate hikes. Tokyo had been closed for Silver Week. When it reopened, it had three days of global selling to absorb in one session.
Germany’s 10-year Bund yield extended its recent rise to 3.58%, its highest level since mid-2009. France’s 10-year OAT yield rose to a new 18-year high of 4.7%, as elevated oil prices and stronger economic data reinforced expectations of further monetary tightening by the European Central Bank. The yield spread between French 10-year OATs and German Bunds widened to about 1.04 percentage points, its widest level since 2012. France’s fiscal position makes it a category of its own: higher energy-related spending linked to the war in the Middle East has added to pressure on public finances, with several forecasters expecting the deficit to stay a little above 5% of GDP this year, broadly similar to 2025.
The US leg of the move is the most covered but arguably the least instructive. The 10-year Treasury note stayed close to its highest level since 2007, while the 30-year yield stood around 5.48%, near 2004 highs. Efforts by Treasury Secretary Scott Bessent to cap long-dated yields through increased Treasury buybacks are widely seen as having had limited impact. Tripling buyback operations to as much as $6 billion did not stop the move. That detail should not be buried.
What makes this week structurally different is the simultaneity. This is not simply another reaction to one central bank meeting. The selloff reflects a much bigger change in how markets are pricing inflation, government debt, and the supply of investible money. Three major sovereign markets, in three different time zones, with three different central banks, all broke to multi-year or multi-decade highs in the same five sessions.
The yen is where the feedback loop becomes dangerous for risk assets. The Japanese yen traded around 158.5 per dollar, staying near two-week lows and close to the key 160 level that could test Tokyo’s tolerance for further yen weakness. The yen weakened as the Bank of Japan’s rate hike last week was viewed as insufficiently hawkish, with two officials dissenting from the decision. Rising JGB yields without a stronger yen is a compressed-spring situation: the BOJ either accelerates tightening and rattles carry trades globally, or holds back and watches the currency slide toward levels that force intervention.
BlackRock’s iShares 20+ Year Treasury Bond ETF TLT fell 1.6% to $80.46 a share, closing at a record low as the yearslong bond market selloff showed few signs of relenting. TLT has lost more than 40% of its value since its 2020 peak. Duration is not a buy here. If the 10-year Treasury yield settles meaningfully above 5%, it would translate into a higher discount rate, meaning anticipated future cash flows would be worth less today, which typically lowers equity valuations.
The Trading Plan
The primary risk for equities is not a single data point next week. It is the persistence of this configuration: yields in Tokyo, Frankfurt, Paris, and Washington all elevated together, compressing the valuation argument for growth stocks and pressuring anything that borrowed cheaply against long-duration collateral.
Investors are currently assigning about a two-thirds probability to a 25 basis point Fed hike at the next meeting. In Europe, rate markets have, at times, priced close to 1 percentage point of additional ECB tightening by late 2027. Neither of those outcomes has been priced into equity multiples with any conviction yet.
Watch 160 on USD/JPY. Watch whether the Bund holds above 3.5%. And watch TLT for any stabilization at current levels before adding equity risk. Until at least one of those three shows a credible floor, the path of least resistance for long-duration assets remains lower.