Dear Reader,
A financial crisis usually doesn’t begin with one company defaulting or one fund taking a hit.
The real danger begins when investors get nervous and start asking for their money back… forcing funds to sell assets, lenders to pull back and credit to dry up.
And very soon, what looked like an isolated problem suddenly spreads across the financial system like wildfire. By the time most investors realize what’s happening, it’s already too late.
Weiss Ratings saw versions of that in 1998, in 2008, and again during the market panic of 2020.
But here’s the most critical part …
55 years of watching financial crises unfold tell us we could be seeing the perfect conditions for another chain sreaction.
And the fallout could reach banks, insurers, annuities, investment funds and retirement portfolios.
That’s why we’ve recorded a special briefing explaining what we’re seeing now … and why we believe investors should take action before the pressure gets worse.
In this presentation, we also reveal five specific steps you can take now to help protect your wealth before this new subprime crisis spreads.
Click here to see our warning before the rush for the exits begins
Good luck.
Sincerely,
Eliza Lasky
Weiss Advocate
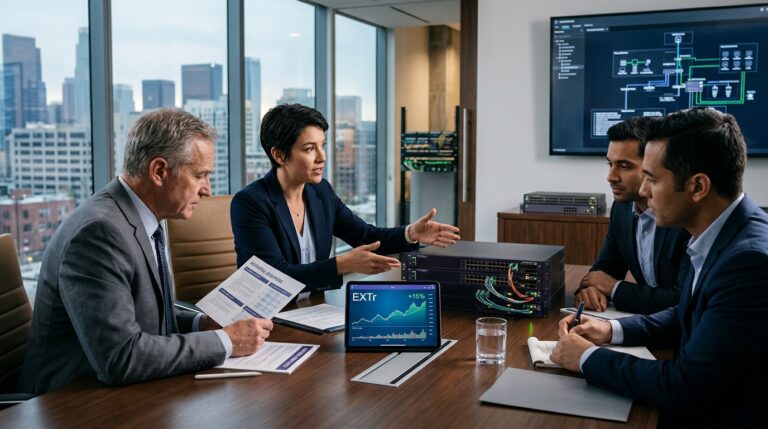
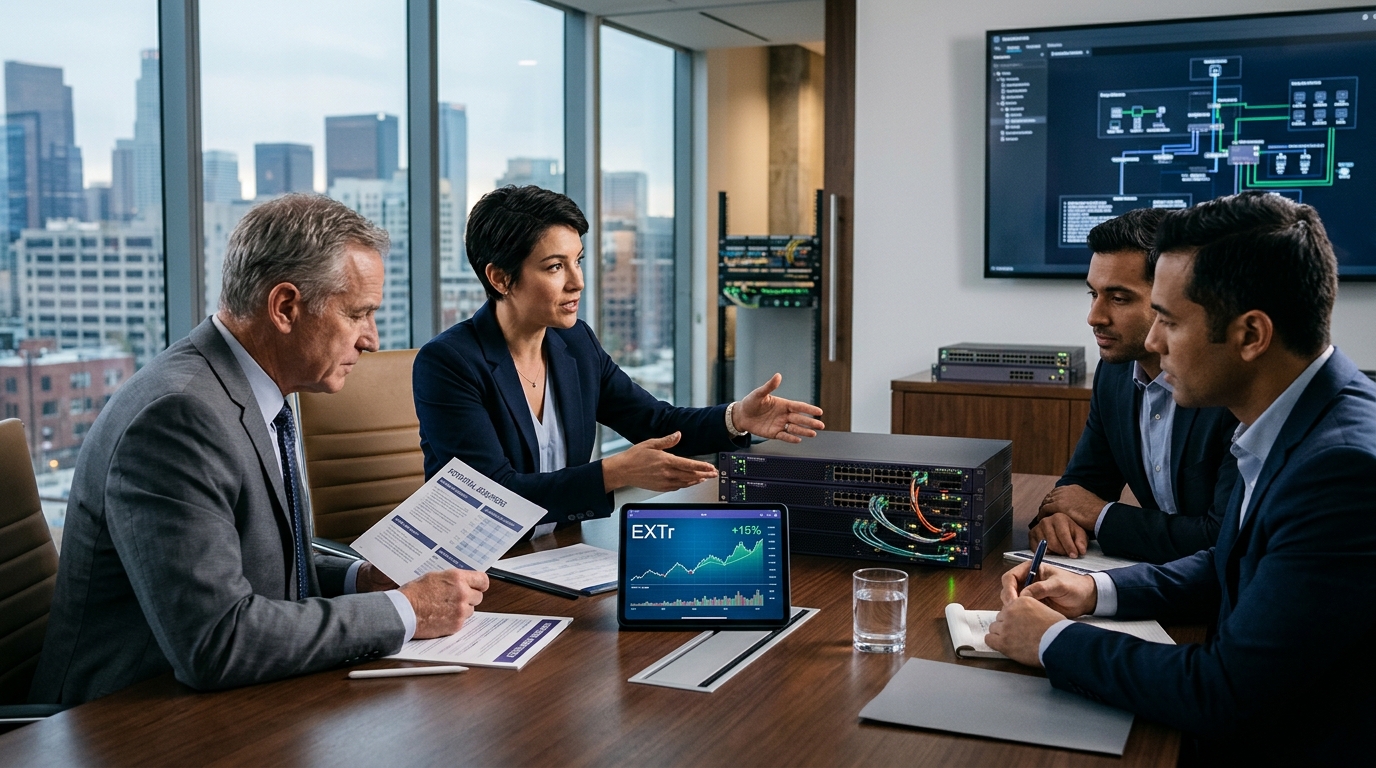
EXTR Is Up 15%. The Bidders Matter More Than the Price.
The stock move is not the story. On November 6, Extreme Networks surged roughly 15% after Reuters reported that the company is exploring a potential sale following inbound acquisition interest. That reaction is straightforward. The interesting question is who is said to be circling, because the three names Reuters cited have almost nothing in common strategically.
Potential strategic acquirers named in the report include Fortinet, Cisco Systems, and NetApp. None has been confirmed as a bidder, and there is no certainty a transaction will materialize. Still, treat each name seriously and you get three distinct reads on what Extreme actually is.
Cisco is the most obvious fit and also the most complicated. Reuters attributed one relevant datapoint to an August earnings call: CEO Ed Meyercord said demand for Platform ONE was accelerating. Buying Extreme would, in theory, let Cisco lean back into the campus and branch edge, but it would also raise the kind of market-share questions regulators have already shown they will ask in networking after HPE’s $14 billion Juniper deal was announced in January 2024 and completed on July 2, 2025. A second mega-deal in the same LAN segment would invite scrutiny.
Fortinet’s interest is more legible. The Reuters item framed the moment as part of broader consolidation as technology companies try to bolster artificial intelligence, cybersecurity, networking, and enterprise infrastructure capabilities. Fortinet’s core pitch is converged security-and-networking; Extreme’s campus and branch fabric would give it more of the wired-and-wireless footprint its security stack is designed to sit on top of. That combination is strategically coherent in a way a pure-networking buyer cannot claim.
NetApp is the outlier. Its focus is data infrastructure and storage, not switches and access points. NetApp has been acquisition-active in 2026, buying DataPelago in July and completing its PEAK:AIO acquisition on November 2. Adding a networking hardware business would be a significant departure. If NetApp is genuinely interested, it likely sees Extreme’s AI management platform, not the cables and chips, as the prize.
That platform is worth examining on its own terms. Extreme said Platform ONE bookings are now over 50% of subscription bookings, up fivefold from the prior year. The company also reported 13% revenue growth in fiscal 2026. And IDC’s second-quarter 2026 Ethernet switch tracker put worldwide Ethernet switch revenue at $18.9 billion, up 43.4% year over year. Extreme is growing into a rising tide.
The harder question is valuation. EXTR closed November 6 at about $24 after the surge. If you want a shorthand for where the consensus sits, one widely followed third-party valuation write-up pegged fair value at $33.50, and sell-side price targets cluster in that neighborhood. A buyer paying a premium well above that zone would be underwriting faster Platform ONE monetization than the market is currently assuming. Meanwhile, the “Magic Quadrant” detail in the draft should be handled carefully: Gartner’s enterprise wired and wireless LAN Magic Quadrant is a real publication, but Extreme has publicly described itself as a Leader in the 2024 edition, so calling it a “visionary” without specifying the exact year and placement is not supportable as written.
Discussions remain in the exploratory stage and no formal offer has been announced. What to watch next: whether Cisco publicly distances itself from the process, which would narrow the field to Fortinet and change the ceiling on any offer considerably.