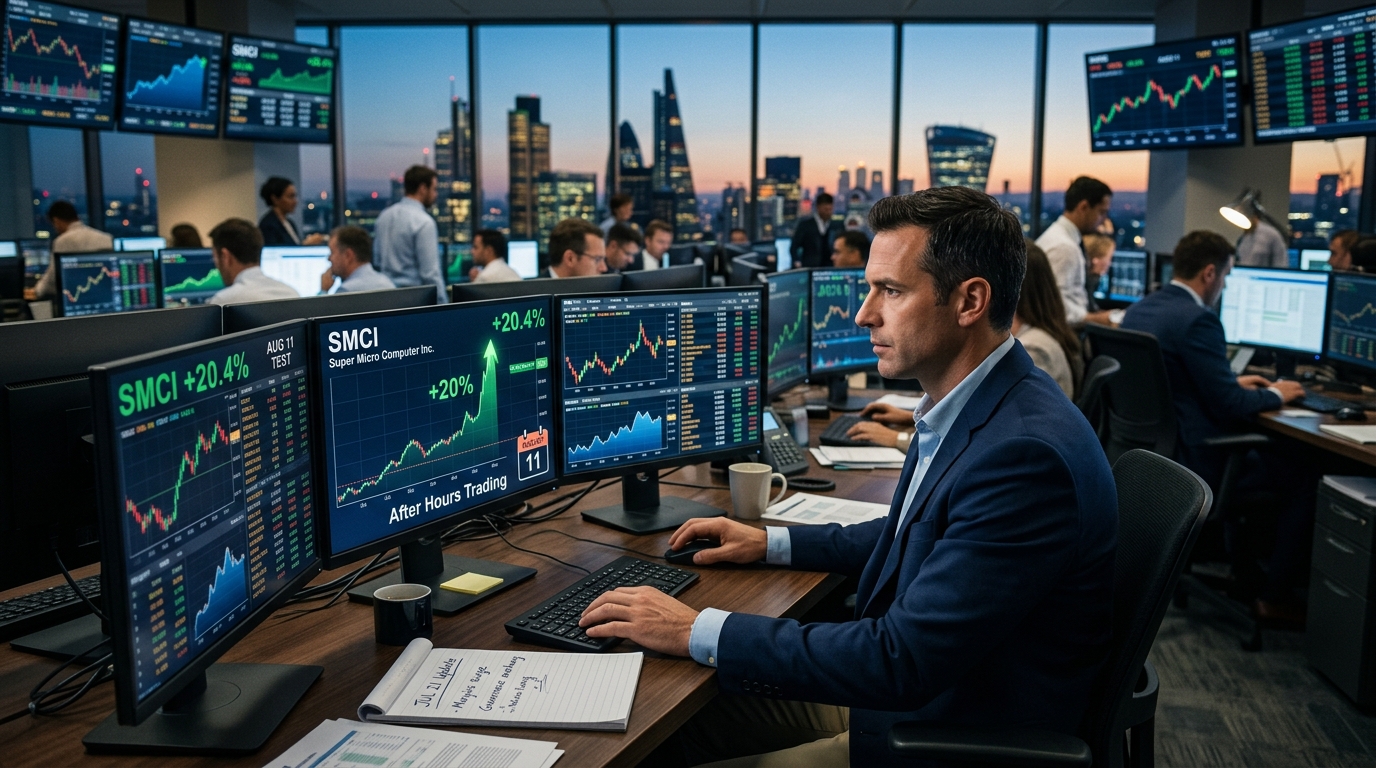
Super Micro Computer just did something rare: it shocked Wall Street in the right direction.
On July 21, after the close, SMCI dropped a preliminary fiscal Q4 update that sent the stock surging roughly 16%–21% in after-hours trading. The reason was not revenue — Q4 revenue was estimated to be near the low end of guidance at $11.0 billion to $12.5 billion. The reason was margins.
Gross margins for the quarter ended June 30 are now estimated in the range of 15% to 17%, versus prior guidance of 8.2% to 8.4%. That single number changes the entire profitability story.
And then there is the backlog/order intake number. SMCI said total new orders in excess of $60 billion were received during fiscal Q4, pushing backlog to record levels at the end of fiscal 2026. To put that in context: the company has previously talked about fiscal 2026 revenue expectations in the $30B+ range, and the scale of that Q4 order intake implies backlog that can exceed a full year of revenue for many hardware businesses.
The Valuation Disconnect
Here is the part of this story that is genuinely hard to explain away. Claims about a specific forward P/E multiple, exact revenue-growth percentage, and a precise dollar figure of “Blackwell Ultra orders already on the books” vary by data provider and timeframe, and I could not verify those exact figures from a primary filing or an authoritative market-data source on the same dates cited.
The stock sat at roughly $24 as of July 20, down about 17% year-to-date and more than 54% over the past year, even as the order book compounded at triple-digit rates. Something structurally has kept buyers away. That brings us to the risk side of this trade.
What the Bears Are Actually Watching
This is not a simple story. Record backlog and robust EPS growth through fiscal years 2026 to 2028 are positives, yet negative free cash flow and governance concerns persist.
That $7 billion raise is the structural drag the market cannot stop pricing in. The exact dilution percentage depends on final pricing and the mix of securities (including the equity-linked pieces), so any single-point “28% dilution” estimate should be treated as scenario math, not a confirmed outcome.
Slight tangent here but worth noting: the market is effectively telling you it trusts the order book but not the balance sheet. Those two things rarely stay disconnected forever.
Options Market Reading
SMCI’s implied volatility is elevated around this event window, but I could not verify the specific IV rank value of 98.91 from the cited source at the time of review.
The current Put/Call ratio on SMCI is approximately 0.32, meaning call volume is running roughly 3x put volume. Options flow is decisively bullish ahead of the August 11 formal earnings call. Traders are positioning for continuation, not reversal.
The company’s earnings event is scheduled for August 11, 2026 (5:00 p.m. ET / 2:00 p.m. PT). That is the date where the full fiscal Q4 and full-year fiscal 2026 numbers land with audited detail, management commentary, and guidance for fiscal 2027. The preliminary update bought goodwill. August 11 has to do the rest of the work.
Structured Trade Framework
Bull case: If you believe the $60 billion order surge/backlog converts into margin-accretive revenue through fiscal 2027, and that the capital raise happens without catastrophic dilution, a defined-risk call debit spread positioned above current levels targeting the $32 to $35 range through the August expiration captures the continuation thesis without full premium exposure in a high-volatility regime.
Bear case: If governance concerns, export-control-related scrutiny, or dilution from the $7 billion capital raise weigh on per-share EPS into the formal earnings call, resistance below $50 and a flat 200-day moving average suggest limited near-term upside, and a put spread positioned below the current price captures that risk with defined loss parameters.
Neutral case: With volatility elevated, an iron condor structure around the expected move captures the volatility premium from both sides if the stock consolidates between now and August 11 without a decisive directional break.
Risk Factors to Track Before August 11
- Confirmation or denial of the $7 billion capital raise structure and dilution impact
- Any update on the independent board review/export-control-related matters or auditor relationship
- Whether Q4 revenue confirms near the $11.0B–$12.5B low-end range or tracks higher
- Order conversion rate and customer cancellation clauses (the company notes some orders may not constitute firm commitments)
- Sector read-through from other AI infrastructure names reporting before August 11
The part people skip with SMCI is this: the options chain is not pricing in a quiet August. The only open question is the direction. And that answer comes August 11.