Copper is around $6.65 a pound today, up nearly 45% over the past year. Freeport-McMoRan (FCX) is still roughly 10% below its late-August peak. That gap is not a mystery: Washington created it, and Washington will likely close it, one way or the other, before year-end.
One Reuters Story, One Very Expensive Session
When Reuters reported September 10 that the White House had not yet finalized its stance on refined copper tariffs, FCX shed about 6.6% in a single day, closing at $71.21. The metal itself recovered quickly, extending gains across four consecutive sessions after the initial drop. Copper’s resilience is telling. Futures pushed back above $6.60 per pound, supported by stronger Chinese demand signals, with the Yangshan copper premium climbing. The equity sold off. The commodity did not. That divergence says something about the nature of the risk investors are actually pricing.
Why the Tariff Uncertainty Hits FCX Hardest
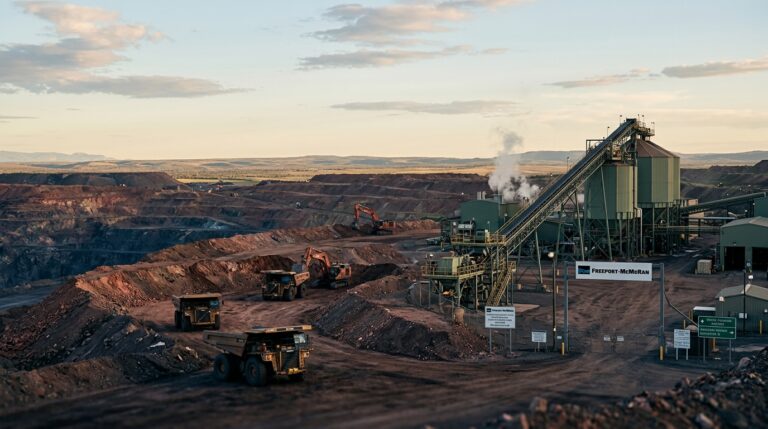
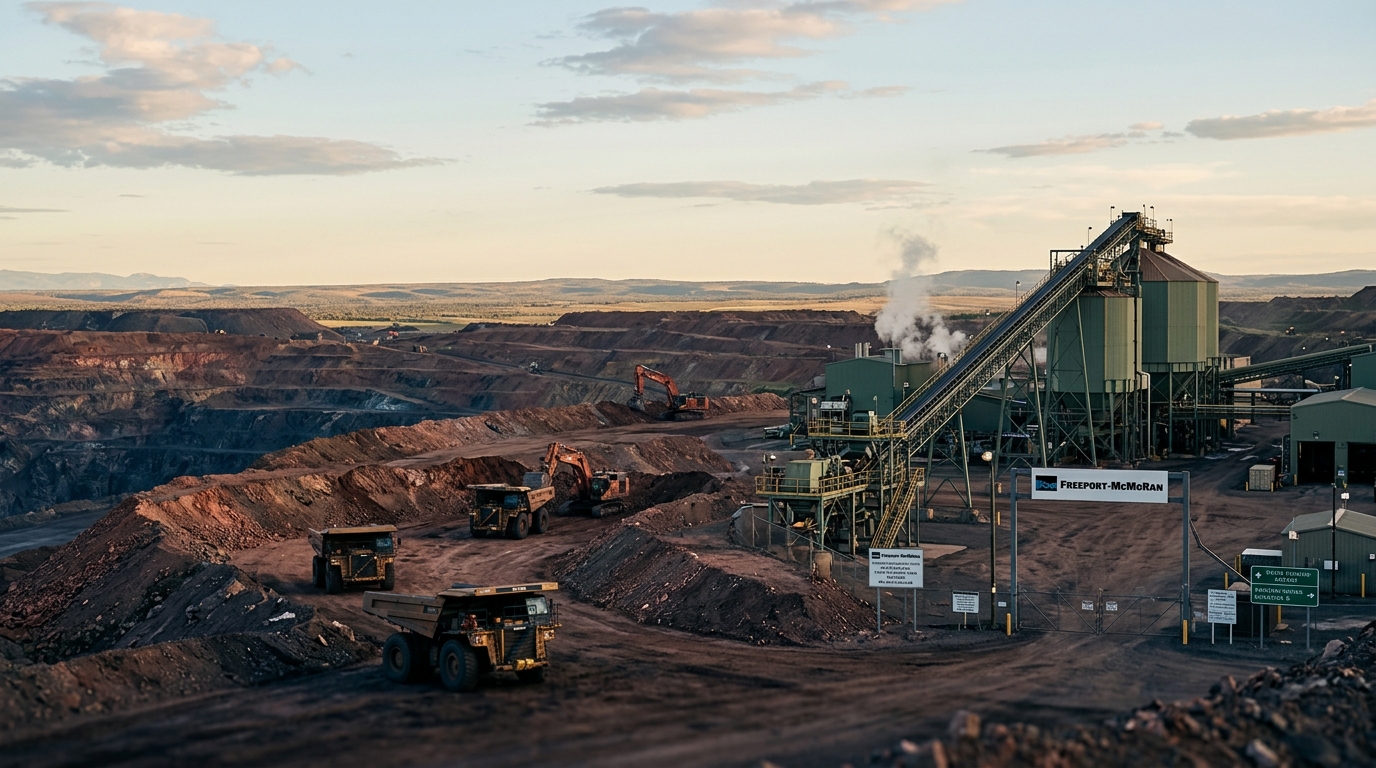
Freeport-McMoRan is the largest U.S.-based copper producer and the most copper-levered name in the peer set, so it moves furthest in both directions when the metal price resets. That leverage cuts both ways. The company supplies approximately 70% of total U.S. refined copper production, which creates a position that no tariff opponent can easily replicate domestically. If cathode tariffs advance toward the January 2027 timeline, FCX is not fighting cheaper imports. It is the domestic supply those tariffs are designed to protect.
A 50% tariff took effect August 1, 2025 targeting semi-finished copper products and copper-intensive derivative products. The White House indicated it would reassess by the end of June 2026 the potential for a refined copper tariff of 15% beginning in January 2027, rising to 30% in 2028. That reassessment remains unresolved. Reuters reported that officials inside the administration are split on whether to move forward with duties on refined copper, torn between the inflationary risk higher metal prices could pose for manufacturers and the upside of jumpstarting mining activity on U.S. soil. The mere possibility of tariffs has already sent copper prices to fresh records, as buyers raced to build up domestic supply, and the ongoing indecision is reportedly keeping producers from routing metal abroad, squeezing global supply. Goldman Sachs, for its part, called the uncertainty itself an opportunity in FCX as recently as September 10.
The Earnings Math Is Already Working
Q2 2026 results, reported July 23, delivered adjusted EPS of $0.74. Net income attributable to common shareholders rose to $984 million from $772 million a year earlier. Unit net cash costs averaged $1.97 per pound in Q2, against full-year guidance of $1.90. The Q2 average realized copper price was $6.17 per pound, leaving a gross spread of roughly $4.20. At today’s $6.65 spot, that spread widens to approximately $4.68 before Q3 numbers arrive.
Management’s EBITDA sensitivity model projects 2027-2028 annual EBITDA of $20 billion at $7 copper versus $13 billion at $5. Each $0.10 per pound move in copper translates to roughly $390 million of annual EBITDA. The metal is currently sitting between those two benchmarks and trending higher. On the operational side, Grasberg Block Cave production rates rose from 34,000 tonnes per day in April to 69,000 tonnes in June, recovering from the September 2025 mud rush. Management projects second-half 2026 copper sales running more than 20% above the first half.
Risks to Watch
The administration could abandon the refined copper tariff entirely, removing the domestic policy premium from the stock. The name still carries an operational overhang from the September 2025 mud rush at Grasberg in Indonesia, with the flagship mine continuing to ramp back toward full capacity through the second half of 2026. The Bagdad expansion is tracking roughly 30% above prior cost projections. Indonesian regulatory approvals for Grasberg’s extended operating rights remain pending. The Fed has signaled that additional rate increases could be necessary, which could weigh on growth-sensitive metals if demand softens faster than supply contracts.
Wealth Takeaway
The structural case for copper, driven by data centers, EV grid build-out, and compressed treatment charges at the mine level, is not in serious dispute. What is in dispute is how much of that case belongs in an FCX stock price versus the copper futures curve. Q3 earnings will be the next hard test. If Grasberg’s volume step-up materializes and realized prices track well above $6.17, the operating leverage that showed up in Q2 should widen further. Long-term investors in FCX are not really betting on a tariff. They are betting that the world needs far more copper than it can reliably produce, and that the company controlling most of America’s refined output is not a bad place to sit while that imbalance plays out.