November 8, 2026
Bonus Content: The 10-Year Auction and CPI Land on the Same Tuesday
Dear Friend,
Quick question.
Want the one stock Elon can’t build without?
I’ll hand it to you today. Free.
It’s not Tesla. It’s not SpaceX.
Every Tesla. Every Starlink dish. Every AI satellite.
Each one runs on a chip Elon doesn’t own. He licenses it. From this company.
And he wants 1,000,000 satellites in orbit.
Every one pays this company a royalty.
Dylan says get in before December 8th.
After that, the easy money’s gone.
Yes, send me the free pick here >>
The Buck Stops Here,
Kelly Maguire
Behind the Markets
P.S. No catch. It’s a public stock you can buy today. The window closes December 8th.
The 10-Year Auction and CPI Land on the Same Tuesday
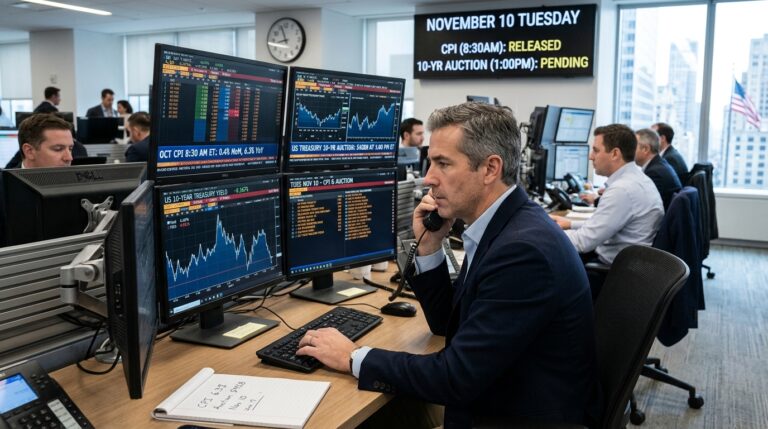
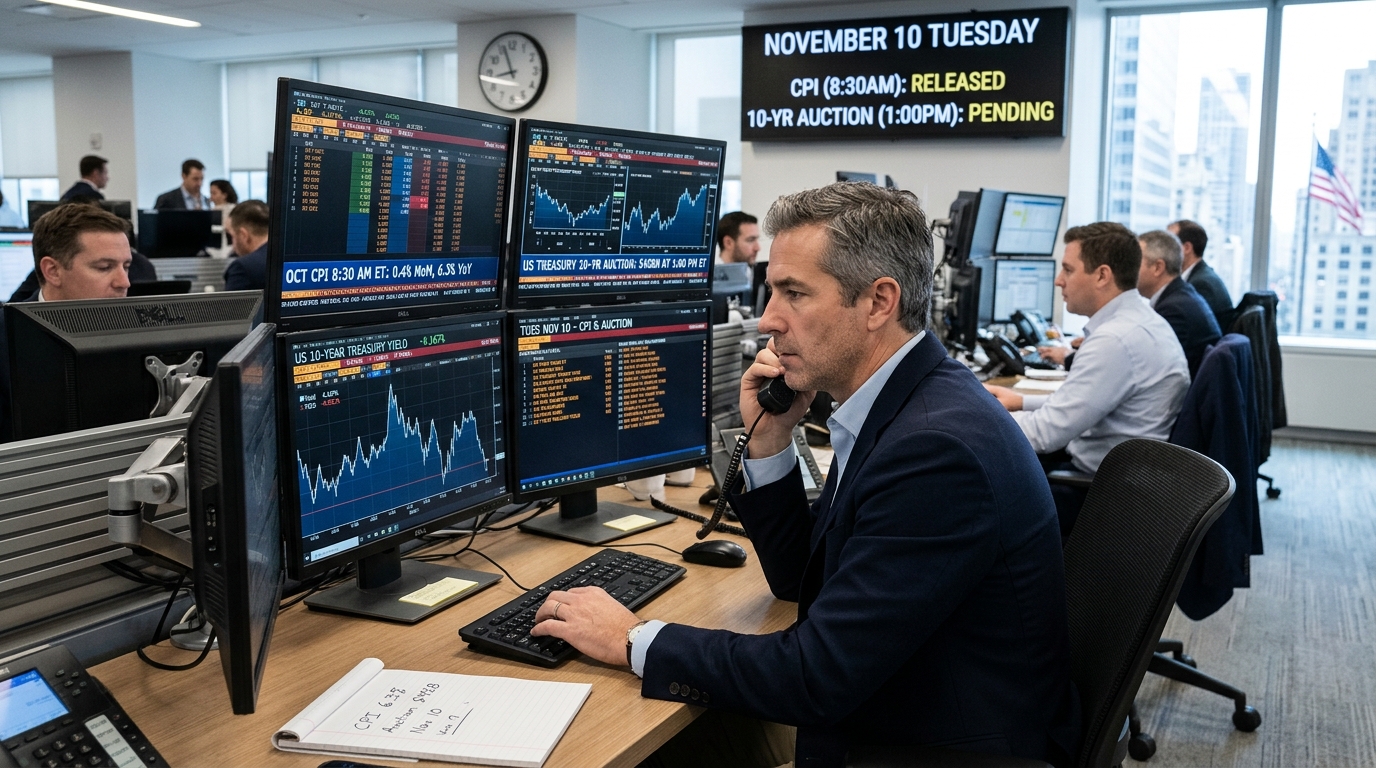
Treasury supply and inflation data are about to collide in a single Tuesday morning. The Bureau of Labor Statistics has October CPI scheduled for November 10 at 8:30 a.m. ET. The 10-year note auction closes at 1:00 p.m. ET on the same day. Six hours separate the two events. The bond market will not get a Wednesday to breathe: Veterans Day falls on November 11, leaving the bond market closed.
Treasury is offering $125 billion to refund approximately $97 billion of privately-held notes and bonds maturing November 15, raising roughly $28 billion of new cash. The package runs $58 billion in 3-year notes Monday, $42 billion in 10-year notes Tuesday, and $25 billion in 30-year bonds Thursday, all settling November 16. That is three days of meaningful supply compressed into a week missing its middle session.
What the Last Auction Cycle Showed
The October auction round established the floor. The October 7 10-year reopening sold $39 billion at 5.300%, the highest yield since August 2000, with bidders putting in 2.77 times the amount on offer and primary dealers left holding just 2.5% of the competitive award. Non-dealer investor take-up reached 97.5%, while indirect bidders, a category that includes foreign central banks, were awarded 80.3%, one of the highest shares on record. Foreign demand at those levels is strong by any measure, but it arrived when yields were near multi-decade highs. This week’s 10-year enters at 4.86%, roughly 44 basis points below that clearing yield.
The 30-year told a harsher story. The October 8 30-year reopening sold $22 billion at 5.618%, the highest since August 2000, up 31 basis points from the prior auction. The bid-to-cover came in at 2.54 and indirect bidders took 72.3%. Demand graded average, not strong, at a generational yield. Thursday’s new 30-year issue arrives at 5.26%, a full 36 basis points below what October required to clear.
The Tuesday Crunch
The sequencing problem is real. CPI drops at 8:30. If the reading runs hot, the when-issued 10-year yield will gap higher into the 1 p.m. auction window. September CPI came in at 3.7% year-over-year. Forecasters are split on whether October accelerates from there, and October payrolls jumped to 165,000 versus the 59,000 Wall Street had expected, in a reading that has raised the probability of a Fed rate hike at the December meeting. CME FedWatch put the probability of a quarter-point December hike at about 73% by Friday. A hot CPI would push those odds higher and hand dealers a 10-year at a yield that still feels tight relative to what policy may require.
Primary dealers cannot walk away. Treasury’s 24 primary dealers are obligated to bid at every auction and make markets in Treasury securities; auctions generally look better when dealers take fewer bonds, because a low dealer share signals stronger end-user demand. In October that was the case. The question for Tuesday is whether end-user buyers show up at a yield 44 basis points south of where they rushed in last month, with December hike odds near 73%.
What to Watch
Treasury also removed the word “at least” from its guidance on keeping auction sizes stable, a signal that desks have read as a possible pivot toward lighter long-end issuance in 2027. That prospective change matters more for the 30-year on Thursday than for Tuesday’s 10-year, but it frames the entire week: buyers who think long-end supply shrinks from here have a reason to absorb duration now.
TLT, which holds 20-year-and-longer Treasuries, had $48.9 billion in assets under management as of November 6 and a 4.77% 12-month trailing yield, making it the most direct instrument through which retail investors track this week’s outcome. A strong 10-year on Tuesday, defined by a stop-through or tight tail and a dealer share below 5%, would likely lift TLT. A tail on a hot CPI day would do the opposite.
TLT is not the only instrument repricing around Treasury yields. Utility stocks have been the bond selloff’s most visible equity casualty, with dividend yields structurally uncompetitive against 10-year paper near these levels.
The number to watch first on Tuesday morning is not the auction. It is the CPI reading at 8:30. If October comes in at or above 3.8%, the 10-year auction that follows will tell investors something the October data could not: whether demand for US debt holds when both inflation and the Fed are still pointing the same direction.