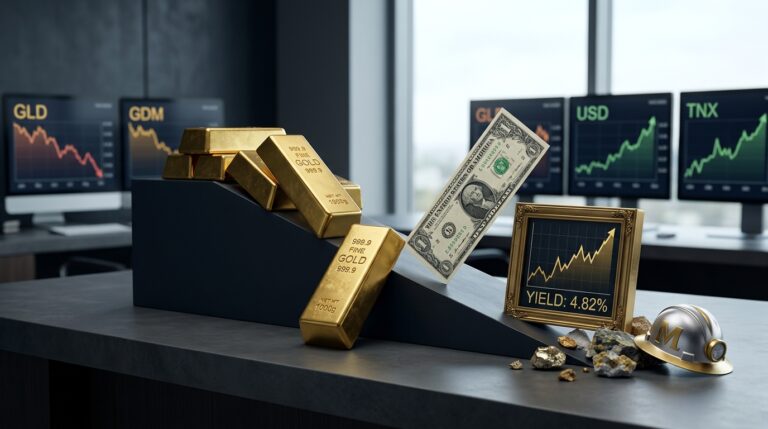
Spot gold touched $3,693.13 in Asian trade Thursday, its lowest level since late September 2025, after a 3.3% plunge on Wednesday that followed the release of the Fed’s October meeting minutes. The minutes showed nearly all officials expect the central bank to lift its key interest rate by a quarter point in December, and the dollar climbed to its highest level since April 2025. By Thursday morning, bullion had bounced to around $3,722, but the recovery looks rented rather than owned.
Three things moved hard at once: gold down more than 3%, the dollar index to 103.7, its highest level since April 2025, and the 10-year Treasury yield holding above 5.10%. These are not three separate stories. They are one trade wearing three different costumes: the market is pricing a higher-for-longer path for rates, and everything priced off that is adjusting accordingly.
What the minutes and subsequent commentary reinforced is simple: inflation is still uncomfortably firm, and officials are leaning hawkish. Fed Governor Christopher Waller said in a CNBC interview Wednesday that inflation is “headed in the wrong direction,” and argued the Fed should either consider a half-point move in December or communicate more clearly that additional increases could follow into 2027. Futures markets, by contrast, have been leaning toward a quarter-point move in December.
What the Miners Are Telling You
The equity miners are where the real signal sits, and the signal is not comforting. Newmont sank about 6.1% Wednesday to close near $104.53. Gold Fields fell about 7.4%. Gold itself fell about 3.3%. When miners fall roughly twice as fast as the metal, that is not noise: it is the market pricing in margin compression at current cost structures, combined with a creeping belief that bullion has further to fall.
Gold miners are under scrutiny on all-in sustaining costs, where inflationary pressures across labor, energy, and consumables have historically squeezed free cash flow conversion. A 10-year near 5.10% is not a neutral backdrop for capital-intensive businesses running high fixed costs. The miners are discounting the spot price and then discounting the operational leverage on top of it.
The Investor Base Is Already Moving
The SPDR Gold ETF (GLD) has seen sizable outflows over the past month, reinforcing the same message the price action is sending. That is not panic, but it is a clear directional signal. Investors who entered gold as a rate-cut beneficiary are exiting as that thesis reverses.
Geopolitical tensions have not been enough to offset the rate story. Oil has been choppy, but gold has been falling as rate fears outweigh the safe-haven bid. That is worth sitting with. When a commodity stops responding to its traditional catalysts, it usually means the dominant force has changed.
The bond market has been signaling this shift for longer than the gold selloff suggests. Aggressive put positioning in TLT — with put-to-call ratios pointing firmly toward higher yields — showed institutional money had already repositioned for a higher-for-longer rate path.
Risks and Counterpoints
The bear case is straightforward: real yields stay elevated, the dollar holds above 103, and gold tests $3,700 or below.
The bull case requires a data surprise. If November CPI softens enough to cast doubt on the December hike, real yields would fall and the dollar would retreat, likely sending gold back above $3,800 quickly. When policy turned more dovish from 2024 into early 2026, gold rallied from roughly $2,000 per ounce to above $5,000. The sensitivity works both ways.
What to Watch Next
The November CPI release is the most important near-term data point. Any softening there reopens the question of whether December’s hike is truly certain. Beyond that, watch Newmont and Agnico Eagle relative to spot gold each session: if miners begin to stabilize while bullion drifts, that is a sign the worst of the equity repricing may be done. If miners keep leading lower, the metal has further room to fall than the spot price alone suggests.