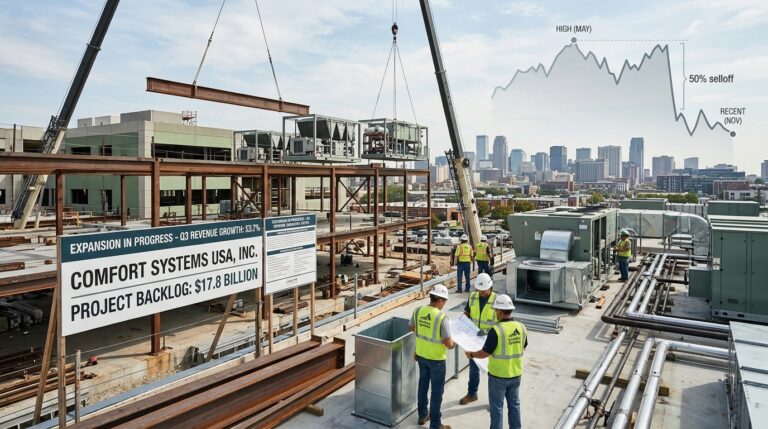
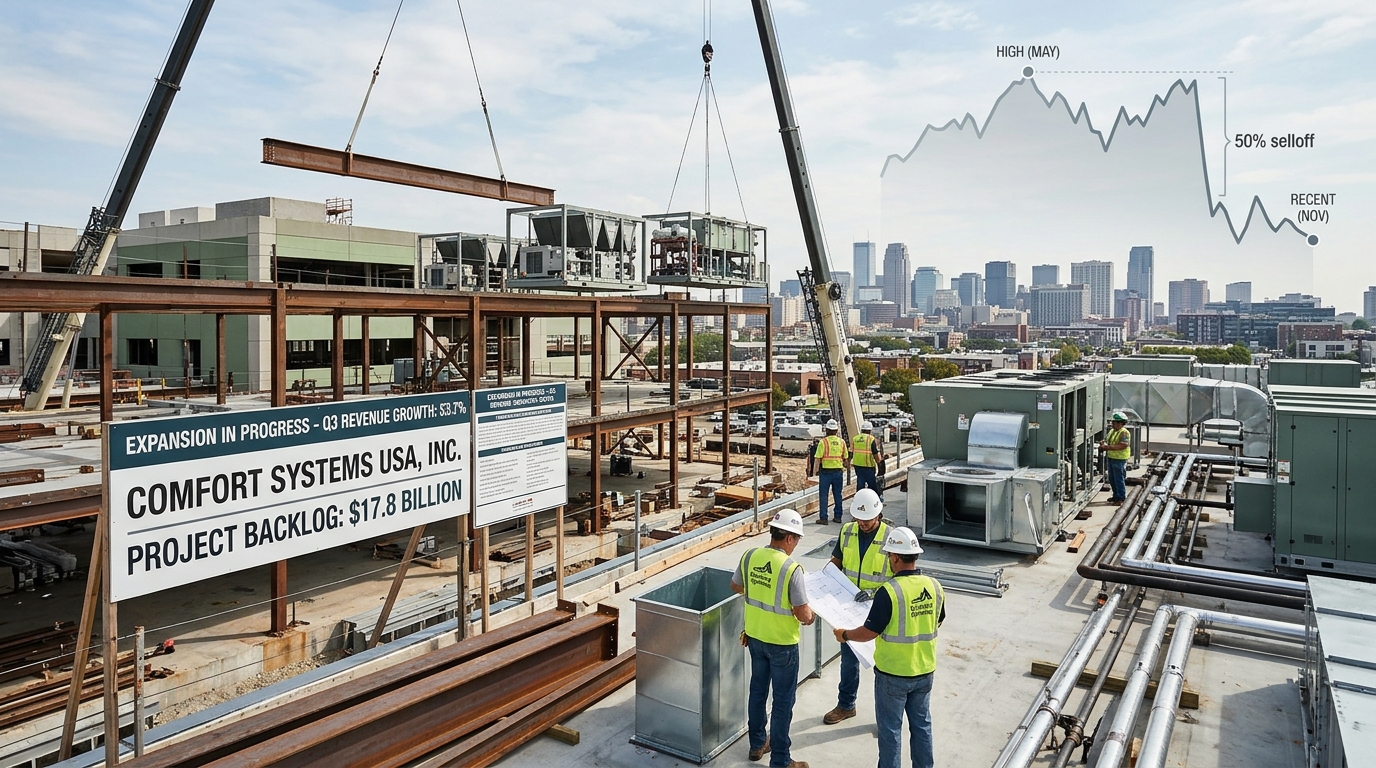
Comfort Systems USA closed November 20 at $1,042.47, down about 50% from the $2,073.99 it reached in May. The company’s latest quarterly results, delivered October 22, showed revenue up about 53.7% year over year to $3.77 billion. EPS came in at $13.91, beating the $12.85 consensus by $1.06. The backlog at September 30 stood at $17.815 billion, up 90% year over year and 27% sequentially. That is the eighth consecutive sequential increase. The business is accelerating. The stock is in collapse.
Why This Stock Now
The disconnect between FIX’s operational results and its share price is not subtle. The selloff began the morning after the Q3 report, when the stock fell 9.1% despite the beat. Then November 4 arrived: data center stocks cratered across the board after Democrats notched major gains in the midterm elections, raising fears about AI infrastructure regulation. FIX dropped 15.1% that day without a single company-specific announcement. It has not recovered.
This week the board expanded its share repurchase authorization to add capacity for up to 1 million additional shares. From January 1 through November 16, the company repurchased 1,552,236 shares for approximately $1.89 billion, funded entirely by operating cash flow. At the current price, buying back stock is cheaper than it has been at any point since late 2025.
The Business
Comfort Systems installs and maintains HVAC, electrical, plumbing, and fire protection systems across 211 locations in 155 U.S. cities. That description undersells what it has become. Technology customers made up 59% of revenue in the first nine months of 2026, up from 42% a year earlier. The company now builds the mechanical and electrical infrastructure inside data centers, with a modular construction business actively serving hyperscalers and frontier AI labs.
Nine-month operating cash flow reached $2.54 billion. Free cash flow was $2.05 billion. Net margin for the trailing twelve months is 13%, and return on equity sits above 58%.
Why Wall Street Is Paying Attention
JPMorgan initiated coverage in November with an Overweight rating and a $1,700 price target, calling Comfort Systems an infrastructure juggernaut. UBS holds a Buy with a $1,900 target. The average analyst price target sits near $1,772, against a current price of roughly $1,042. Institutional ownership exceeds 96% of shares outstanding. Amundi bought an additional 156,069 shares last quarter, bringing its total position to 292,904 shares valued at over $580 million at the time of purchase.
What’s Driving the Opportunity
The backlog is the most compelling single data point. At $17.8 billion, up 90% in a year, it covers roughly twice Comfort Systems’ full-year 2025 revenue. Backlog at this scale does not vanish overnight. These are contracted projects with defined scopes and committed customers. Even if the pipeline slowed materially from here, the company has meaningful revenue visibility already in hand.
Q3 adjusted EBITDA reached $667.9 million, up 61.4%. Operating income rose 64.8%. Diluted EPS for the first nine months of 2026 was $36.94, against $19.52 in the same period a year earlier.
What Could Go Wrong
Concentration is the core risk. When 59% of your revenue depends on one customer segment, a slowdown in that segment is not a headwind, it is a structural problem. If Democratic-led legislation results in meaningful data center permitting restrictions, project timelines slip and backlog conversion slows. That is the bear case the market priced in November 4, and it has not let go.
Insider selling prior to the Q3 report was notable: executives divested more than $43 million of shares in the three months before results. The forward P/E of roughly 18 times assumes growth moderates sharply from current levels. If margins compress as project mix shifts or labor costs rise, the multiple may not expand even if sentiment recovers.
The Bottom Line
A 90% backlog increase and 54% revenue growth do not normally produce a 50% share price decline. Comfort Systems has been punished for political risks that have not yet translated into any change in its contracted business. The buyback expansion signals that management sees the same gap the numbers do. At 18 times forward earnings with $17.8 billion in backlog and $2 billion in annual free cash flow, the case for FIX does not require the AI trade to fully recover. It requires the business to keep converting what it already has booked.