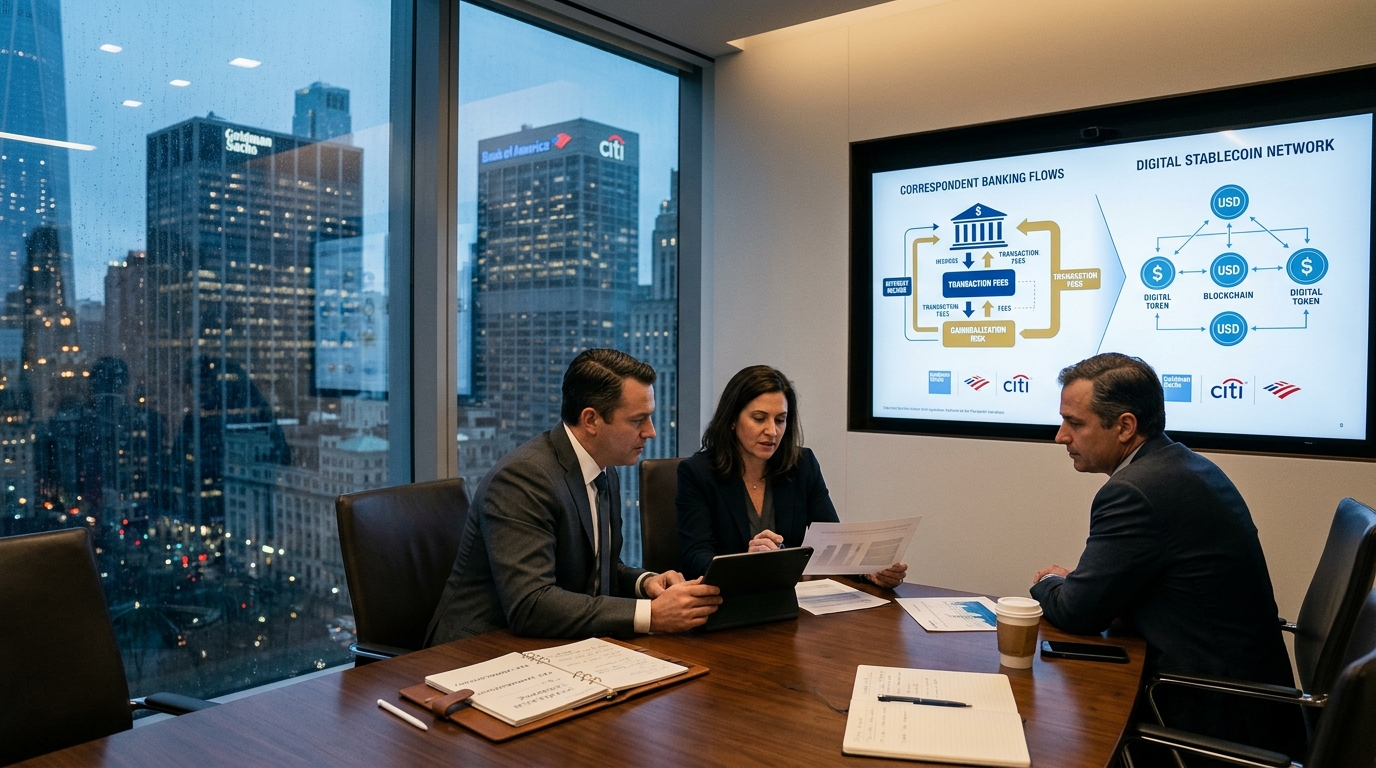
The stablecoin market now has its most credible institutional challenge yet. On September 1, Bank of America, Citi, Goldman Sachs and 18 other financial institutions committed to establish a stablecoin company during the second half of 2026, with a dollar-denominated stablecoin targeted for launch in the first half of 2027, and an expansion into additional G7-currency stablecoins with a euro offering identified as the priority. The consortium is global in scope: it includes Deutsche Bank, among institutions from North America and Europe.
Every investment committee meeting this week will ask two questions. The first is obvious: what does this do to Circle and Coinbase? The second is the one nobody wants to say out loud: what does this do to the correspondent-banking fees these same institutions currently collect?
The Bull Case for the Consortium
The consortium says its stablecoin will target wholesale, institutional and retail markets, including use cases such as cross-border payments and digital asset settlement. That is precisely where traditional banking makes money the old-fashioned way. SWIFT transfers can take longer than domestic real-time systems, with timing dependent on banks, cutoffs, time zones and local market infrastructure. A bank-issued stablecoin designed to be GENIUS Act-compliant that settles cross-border payments faster at a fraction of the cost would be a genuinely disruptive product, even if the institutions building it currently profit from the friction it replaces.
The scale here matters. Membership has grown since an earlier October 2025 initiative involving ten banks exploring a reserve-backed model. Organizers plan a 1:1 reserve-backed token available on public blockchains, and the venture intends to meet applicable GENIUS Act and MiCA requirements before beginning global operations. Regulatory compliance built in from day one is a structural advantage that crypto-native issuers spent years trying to retrofit.
The Bear Case: Cannibalism and Coordination
The harder problem is internal. The same banks anchoring this consortium run correspondent networks that generate substantial fee income from the very cross-border flows this stablecoin is designed to capture. Bank-issued stablecoins may view the float business as complementary to broader banking revenue, making the margin less critical, but that framing papers over a real conflict. When a Goldman or Citi corporate client routes a supplier payment via the consortium token instead of a wire, someone inside that bank loses a fee.
Coordination risk is equally serious. Details such as the stablecoin’s name, issuance structure and reserve asset management have not been disclosed. Twenty-one institutions with competing compliance frameworks, technology stacks, and client relationships agreeing on governance is not a given. Circle CEO Jeremy Allaire has argued publicly that stablecoins are network-effect businesses and that large consortia tend to coordinate poorly. That critique applies here with even more force, given the number of sovereign jurisdictions represented.
What This Actually Does to Circle and Coinbase
Circle’s stock declined about six percent following the announcement, reflecting investor concerns about intensified market competition for USDC. That reaction is rational but possibly overstated in the near term. USDC’s distribution across DeFi protocols, layer-2 networks, and institutional trading platforms gives it the liquidity and integration depth that a corporate treasury needs before committing, and that infrastructure took years to build, representing a genuine barrier to replication for new entrants.
Coinbase’s exposure is more nuanced. Stablecoin revenues contributed $305 million in Q1 2026, driven by average USDC held in Coinbase products reaching a new all-time high of about $19 billion. A bank-branded stablecoin targeting institutional and wholesale clients would compete directly for that balance. Yet Coinbase has already hedged: CEO Brian Armstrong has positioned the company as a multi-stablecoin platform supporting multiple issuers, with new consortium participation potentially creating additional business and revenue opportunities including FX trading.
Stocks to Watch
Circle (CRCL) faces the most direct threat. USDC’s circulating supply was about $73.6 billion as of September 1, 2026. A second well-capitalized rival compounds competitive pressure, though the H1 2027 timeline gives Circle runway to deepen enterprise integrations.
Coinbase (COIN) is exposed through its USDC revenue share with Circle but partially insulated by its role as a multi-stablecoin distribution platform. The consortium’s token could eventually appear on Base, which would be revenue-generative rather than dilutive.
Bank of America (BAC), Citi (C), Goldman Sachs (GS), Wells Fargo (WFC) are the ones whose internal economics deserve the closest scrutiny. The efficiency gains from their own stablecoin are real. So is the fee revenue they would route around.
Visa (V) and Mastercard (MA) sit in an interesting position. Both run active USDC settlement integrations already. A bank-consortium token built on public blockchains could either expand the addressable market for card-adjacent settlement or become a substitute rail. Either way, the stablecoin market is no longer a crypto story. It is a banking infrastructure story, and these are infrastructure incumbents.