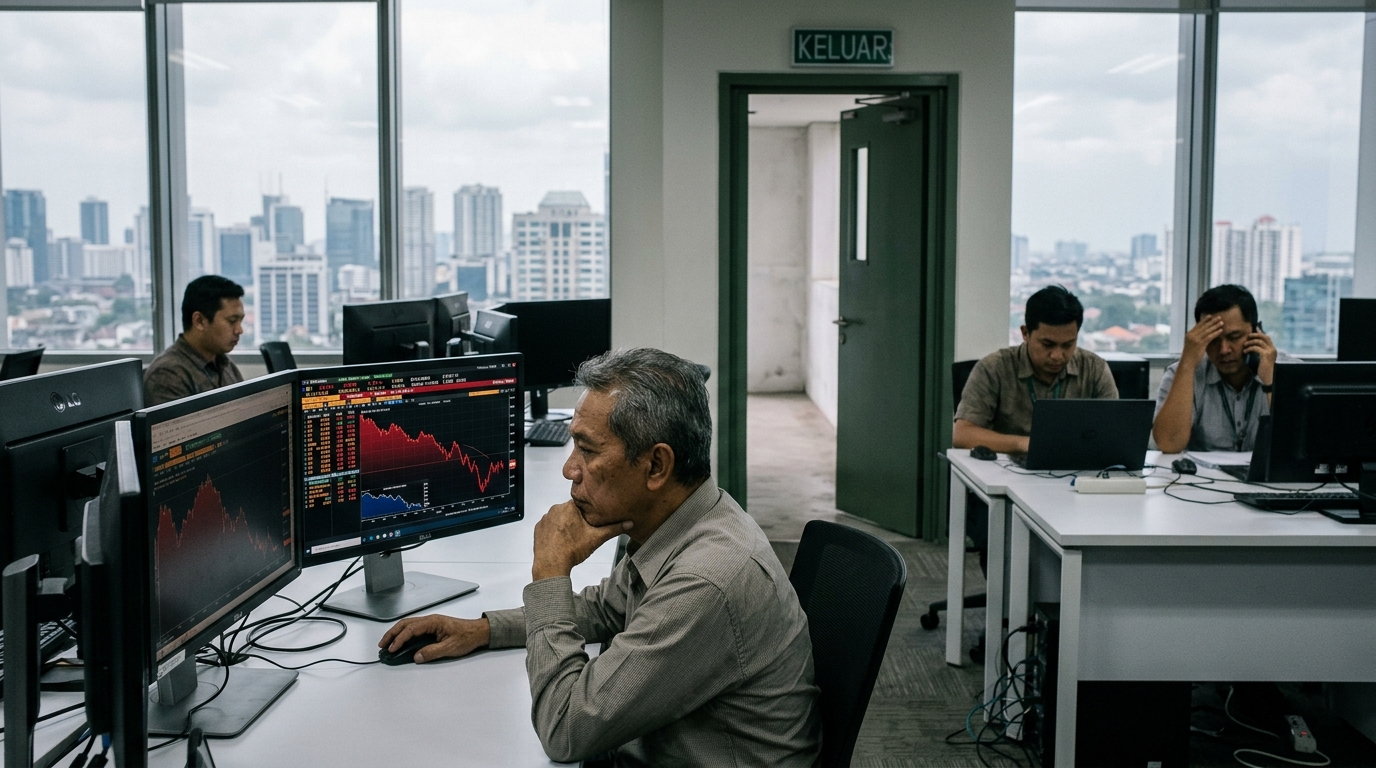
The Jakarta Composite Index did not need a final decision to fall apart. It needed only a question.
MSCI announced it is launching a consultation on a proposal to reclassify Indonesia as a Standalone Market, saying the country’s continued classification as an Emerging Market is “no longer appropriate.” That language alone was enough. The Jakarta Composite opened about 8% lower, triggering a 30-minute trading halt, and by intraday trade was down about 11%, its worst one-day drop since 1998, while the rupiah weakened to around 18,035 per dollar.
That is the real signal buried under today’s chaos. A consultation, with a final decision not due until June 2027, produced a circuit-breaker event. The bid for Indonesian equities was already so thin that the mere possibility of reclassification caused the kind of collapse normally reserved for actual crises.
MSCI’s message was unusually blunt for a consultation notice, with the firm citing “significant concerns around market dysfunction, including continued suspected coordinated trading behaviour and lack of evidence of meaningful enforcement,” and adding that a downgrade to Frontier Market “would not properly recognize the depth of the market problems.” Standalone, not Frontier, is the category MSCI has in mind. Argentina, Lebanon and Palestine are among the markets that carry the standalone designation.
What the Numbers Reveal
The Jakarta Composite fell about 10.6% on the day, taking its year-to-date decline to roughly 39%. That context matters. Foreign investors had already net sold about $4.7 billion in Indonesian equities this year before today’s session. UBS estimated that a confirmed reclassification could trigger roughly $4 billion of passive outflows from Indonesia, with active investors potentially adding a further $15 billion. The passive selling is forced and mechanical. The active selling is discretionary and harder to reverse.
The proposed move would represent a double downgrade for Indonesian equities, bypassing frontier status entirely. That framing tells you what MSCI thinks of the reform progress Jakarta announced in April.
The Indonesia shock does not land in isolation. Emerging-market fund managers were already reassessing EM allocation after China’s industrial profit growth decelerated sharply through the summer.
Where It Shows Up
For investors outside Indonesia, the most direct exposure runs through EIDO, the iShares MSCI Indonesia ETF. The fund’s NAV was $11.69 as of October 15, with a year-to-date return of about negative 36%. It is not just an Indonesia story. A confirmed downgrade would force passive funds tracking the MSCI Emerging Markets Index to liquidate Indonesian holdings entirely, concentrating selling pressure and raising questions about how orderly that exit could be for a market that just needed a halt to manage today’s volume.
Forced passive liquidation does not happen in isolation. Rising sovereign yields across developed markets have already tightened the conditions under which passive EM funds attract or retain capital.
Mirae Asset Sekuritas analyst Wilbert Arifin warned that large-cap stocks with high foreign ownership face the most vulnerability, and estimated that passive foreign fund outflows could reach $3 billion if MSCI implements the reclassification. Samuel Sekuritas pegged the figure higher. The broker projected potential foreign fund outflows of Rp105 trillion to Rp132 trillion, equivalent to roughly $5.8 billion to $7.3 billion.
Risks and Counterpoints
FTSE Russell has maintained Indonesia’s emerging market status, leaving institutional assessments divided. That split matters because some active managers benchmark against FTSE rather than MSCI, and their mandates would not force selling. The MSCI consultation runs until April 30, 2027, with a final decision due by June 30, 2027, leaving Indonesian authorities months to demonstrate progress. MSCI said it expects to proceed with the proposed standalone classification unless there is clear evidence of material improvements in governance and market functioning, which is a high bar but an explicit one.
What to Watch Next
The rupiah’s trajectory from here is the secondary pressure gauge. The currency slid 0.6% to about 18,070 per dollar today, its weakest level since late July. A sustained move through 18,500 would signal that the foreign exit is spreading beyond equities into broader Indonesia exposure. Watch also for any formal response from Bank Indonesia on whether it will defend the currency or let it absorb the shock. The consultation deadline in April 2027 sets a long clock, but capital markets do not wait for official timelines. Today proved that.