The question institutional investors should be asking this morning is not whether the Anglo American-Teck merger closes. It probably does. The question is what Beijing’s conditions cost every future deal in critical minerals, and whether copper’s price already reflects a world where China can direct concentrate flows by fiat.
Why Wall Street Cares
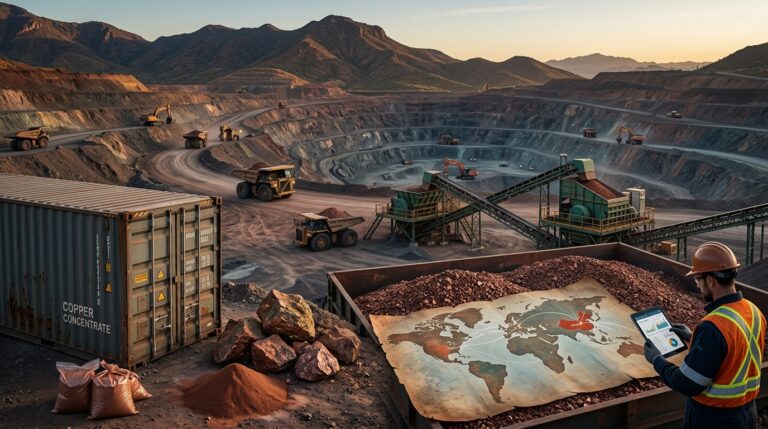
Reuters reported Friday, October 2, 2026 that China’s antitrust regulator has asked Anglo American to commit to supplying China with a steady flow of copper concentrate as a condition for approving its proposed $54 billion merger with Canada’s Teck Resources. The merger has received approval from all regulators where the companies operate except China. That asymmetry is the story. Canada cleared it. The European Commission cleared it. Beijing is the last gate, and Beijing has decided to charge a toll measured in guaranteed raw material rather than cash or divested assets.
As a major consumer of both companies’ copper, China has effective veto power over the merger, and has historically leveraged its antitrust power over megadeals to extract strict “behavioural remedies” to protect its domestic industrial supply. What is new here is the specificity. Reuters reported that China’s State Administration for Market Regulation has asked for assurances on copper concentrate supply, including volumes sold through traders. That last clause matters: it closes the workaround of routing volumes through intermediaries to obscure destination.
The Bull Case for Compliance
Both companies have said they expect the deal to close within 12 to 18 months of its September 9, 2025 announcement, which implies a latest-expected closing window that runs into March 2027. Anglo American told Reuters it is making “good progress” and working constructively with SAMR through its structured review process. The remedies sought do not include asset sales at this stage, which is meaningful: behavioral commitments on supply are operationally manageable and do not require Anglo Teck to give up producing assets. From that narrow angle, the deal survives intact.
A combined company would be a top five global copper producer, but the merger’s logic is not confined to copper market share. SAMR’s demand is not grounded in conventional antitrust logic. It is industrial policy dressed in regulatory language.
The Bear Case for Copper Markets
The second-order consequences are harder to dismiss. China’s smelting industry produces about half of global copper smelting capacity, and it is dealing with an acute concentrate squeeze. Reuters reported on September 28, 2026 that Chinese refined copper output is expected to grow only 3% to 3.4% in 2026, the slowest since at least 2000, due to concentrate and scrap shortages and falling sulphuric acid prices. Beijing is not extracting these commitments from a position of abundance. It is extracting them from desperation, which makes the commitment harder to walk back once granted.
Analysts have warned that steering concentrate toward China could pressure non-Chinese smelters and accelerate the drift from annual benchmarks toward more index-linked spot pricing for treatment and refining. That reset in how concentrate is contracted globally would be a structural change, not a cyclical one.
What Investors Are Missing
The precedent is the real exposure. Executives at Glencore, Anglo American, and Rio Tinto have said antitrust reviews and national interest considerations are becoming more prominent factors when assessing potential transactions involving copper and other critical minerals. What SAMR has done here is transform the merger review into a supply contract negotiation. Every portfolio manager modeling a future copper major acquisition now has to discount for Beijing’s right to attach offtake conditions to approval. That is not a risk that was in deal models two years ago.
The pattern is already spreading: Anglo’s sale of its Nickel Brazil assets to China’s MMG drew preliminary competition concerns from the European Commission over fears that supply of low-carbon ferronickel could be diverted away from European markets. Two megadeals, two jurisdictions, two regulators demanding guaranteed flows. The mining M&A premium just got more expensive to justify.
Stocks to Watch
Anglo American (AAL / NGLOY): The immediate overhang. If SAMR’s terms prove restrictive on pricing or volume flexibility, the merged entity’s earnings power in copper is lower than consensus models assume. Watch for guidance revision once terms are finalized.
Teck Resources (TECK): The deal arb trades tighter or wider on every SAMR headline between now and the companies’ latest expected closing window in March 2027. Teck shareholders are fully exposed to Beijing’s timeline, and Beijing has shown no urgency.
Glencore (GLEN): The quiet beneficiary. If Anglo Teck’s concentrate is effectively committed to Chinese smelters under long-term terms, Glencore’s marketing arm gains pricing leverage on uncommitted volumes elsewhere. Its trading desk has been in this business longer than any competitor.
Freeport-McMoRan (FCX): The independent copper pure-play that institutional money pivots to when integrated majors carry regulatory complexity. A prolonged SAMR review extends that trade.