Friday’s jobs report was supposed to set the tone for the week. It didn’t last the weekend. This morning, European and U.S. equity futures turned lower as traders absorbed what France’s sovereign bond market has been saying since October 1, 2026: the country’s fiscal credibility has deteriorated past a threshold most investors did not think possible.
Market Snapshot
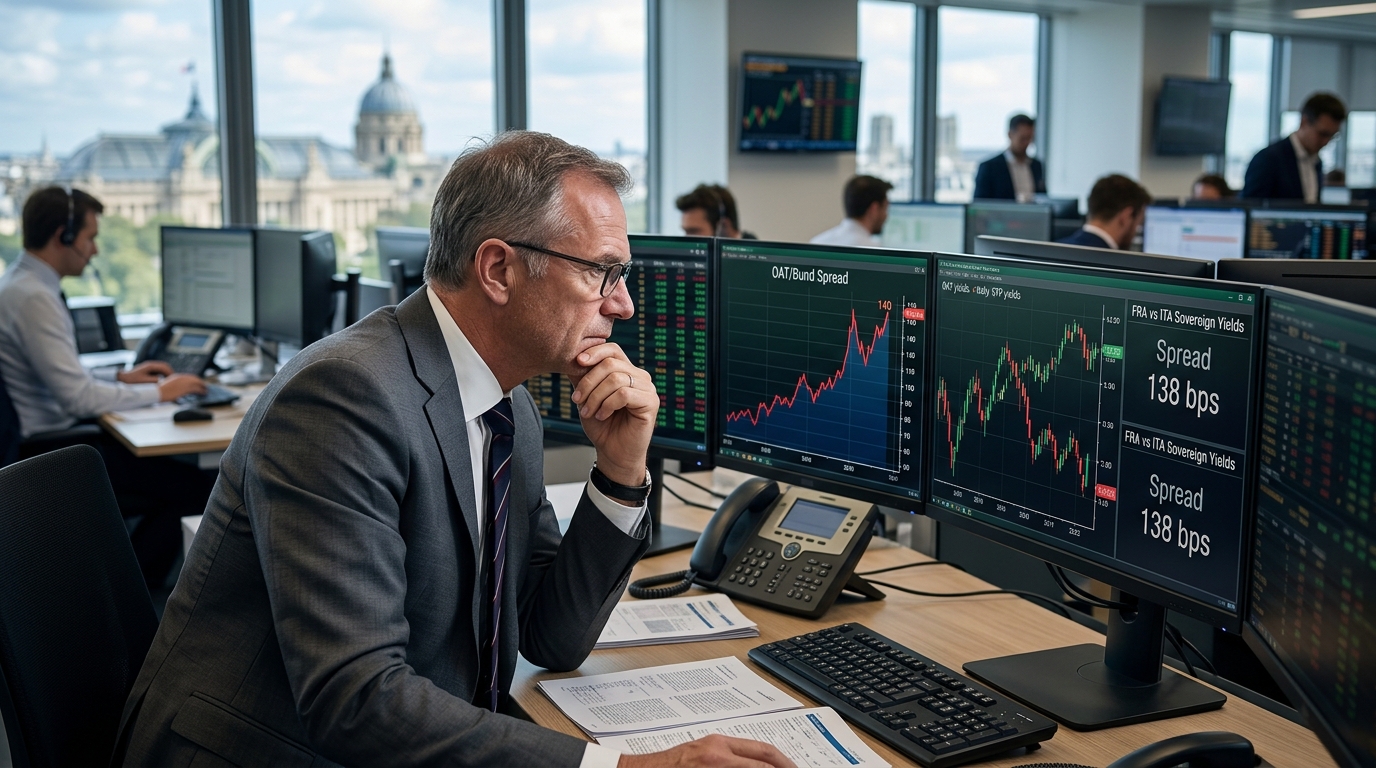
France’s OAT/Bund spread widened to around 130 basis points after the October 1 budget unveiling, leaving France trading wider than Italy. That is not a rounding error. Italy carries debt-to-GDP of roughly 140%, and Greece is higher still, yet Italy has lately been viewed as more creditworthy on a relative basis. The inversion of that long-standing hierarchy is what the bond market is saying this morning, and equity futures are listening.
France faced the sharpest move, with its 10-year OAT yield climbing to roughly 4.90% to 4.92% on October 1, its highest level since June 2002. The spread between French OATs and German Bunds pushed above 150 basis points on October 2, the widest since late 2011, before pulling back to around 140 basis points. The deterioration in France’s borrowing conditions is having very concrete consequences: the weighted average yield on French medium- and long-term debt issuance has reached about 3.55% so far in 2026, compared with 3.14% in 2025.
The euro weakened sharply as focus on France’s debt intensified, with Reuters describing EUR/USD at a 17-month low on October 5 and EUR/CHF lower as well. European equities sold off broadly, with the Stoxx Europe 600 down 1.3% on Thursday while the S&P 500 gained 0.2%. That divergence is the clearest summary of where capital is flowing.
Stocks in Focus
French CDS rose 25 basis points in the last three months alone, versus roughly 13 basis points for Italian CDS. CDS for BNP Paribas, Societe Generale, and Credit Agricole hit their highest levels since April 2025, while a broader index of European bank CDS is only at three-month highs.
- BNP Paribas (BNP.PA): BNP earnings are due October 28. France accounted for just 26% of BNP’s 2024 revenue, which limits direct sovereign exposure relative to peers.
- Societe Generale and Credit Agricole: Societe Generale and Credit Agricole had higher domestic exposure at 41% and 47%, respectively. Wider sovereign spreads threaten to compress net interest margins and may force French banks to mark down bond holdings.
- AXA: The insurer holds a large OAT portfolio as part of its insurance reserves. Sustained spread widening raises mark-to-market pressure on fixed-income assets and elevates refinancing costs on maturing liabilities.
Sector Watch
European financials are the epicenter. The spread dynamic influences the cost of bond financing and, indirectly, bank credit, and a sustained widening trajectory weighs on long-term projects, particularly in capital-intensive sectors. Defensive rotation into German Bunds is the offsetting trade. Bund yields fell as investors moved to safety, compressing the spread from the demand side. That dynamic has limited the ECB’s room: the bar for using the ECB’s Transmission Protection Instrument remains high.
Catalyst Calendar
- Late November to mid-December window: The two budget bills must be formally filed at the National Assembly by October 6, with plenary debate starting October 13. From the filing date, parliament has 70 days to complete the procedure for the state budget, pushing the main deadlines into late November through mid-December. That first-reading window is the initial market test.
- BNP Paribas earnings: October 28. The first major French bank to report since the OAT spike. Guidance on funding costs and sovereign exposure will move the sector.
- ECB speakers this week: Any signal on willingness to address spread widening via bond purchases would compress the OAT/Bund differential sharply.
Technical Radar
If the €54 billion package passes substantially intact and the OAT/Bund spread compresses back below 80 basis points within 60 days, the crisis framing is premature. At current levels, the one-year average around the mid-70s basis points represents a potential compression target of more than 50 basis points. That is a wide range, and it means the spread itself is the chart that matters most this session, not price action in U.S. indices.
Risk Radar
Analysts are sceptical about both the appetite for the planned pace of deficit reduction and the macroeconomic assumptions underpinning the budget. The plan has already drawn scrutiny from France’s fiscal watchdog, which warned that the budget’s economic assumptions are optimistic.
With presidential elections approaching in spring 2027, candidates’ fiscal plans remain too vague to offer reassurance, and markets are increasingly concerned about the race becoming a contest between the far right and far left. That political tail risk is the premium embedded in the spread above and beyond the deficit arithmetic.
S&P Global Ratings already cut France to A+ from AA- in 2025. Fitch has kept France at A+ with a stable outlook but identifies rising debt, persistent deficits, weak potential growth, and political fragmentation as central risks. A further downgrade could force selling from index-constrained buyers.
The Cheat Sheet
- Top Market Theme: A eurozone core sovereign trading wider than Italy has broken a foundational assumption in cross-asset positioning, and nothing in Friday’s payrolls changes that.
- Stock to Watch: BNP Paribas. Most diversified of the three major French banks, with earnings October 28 as the first real read on how sovereign stress is flowing into bank financials.
- Sector to Watch: European financials. Spread widening is a direct hit to net interest margins and bond holdings across the sector.
- Biggest Risk: A fresh bout of French political instability during the budget window would send the spread wider.
- Biggest Opportunity: German Bunds as a safe-haven long against OATs. The spread has room to compress sharply if the vote passes, or to widen further if it fails.
- One Thing to Remember: French interest payments are projected to be a bit above €91 billion in 2027, up from roughly €79 billion in 2026. At current yields, those numbers get worse with every week the spread holds near current levels. The coming budget votes are not just political. They are actuarial.