November 5, 2026
Bonus Content: Commerzbank’s Best Nine Months Show Why Europe’s Banks Beat US Tech
Attention Traders…
If you’re willing to be at your computer between 9 am and 10:45 am on most weekdays…
I can show you one simple trade that can potentially bankroll your retirement.
Hi… I’m Dave Aquino and I help everyday Americans go after their retirement goals sooner… by teaching them how to master the retirement trade.
The Retirement Trade is designed to be used every morning between 9am and 10:45am eastern time.
Why this window?
Well… I can’t share that information here on this page…
But don’t worry because you’ll discover the exact reason why inside the free report you see pictured below…
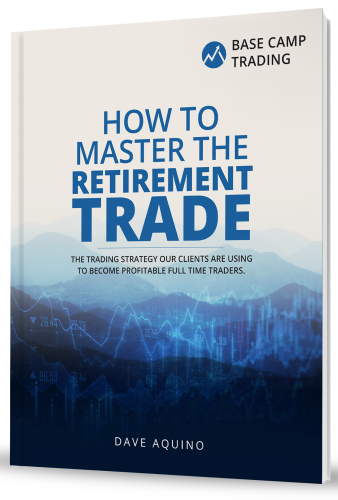
And it’s yours – for FREE!
But please don’t delay, because it might not be free for long.
Commerzbank’s Best Nine Months Show Why Europe’s Banks Beat US Tech
While the Nasdaq 100 was grinding through its third correction of 2026, down more than 10% from its October 6 record, Commerzbank was quietly assembling the best nine months in its history. That contrast is not coincidence. It is a rate-curve and rotation story, and Thursday’s results put a number on it.
What Actually Moved
Commerzbank, Germany’s second-largest listed bank, reported a sharp jump in profits in its latest quarterly update, extending what it has described this year as record momentum. Earlier 2026 updates showed operating profit hitting €1.4 billion in the first quarter and the bank raising its 2026 net result target to at least €3.4 billion, alongside a full-year revenue outlook of around €13.2 billion. The bank has also said net interest income was around €2.0 billion in the first quarter, and net commission income reached about €1.1 billion.
Commerzbank has consistently framed 2026 as another record year in the making, with management repeatedly pointing to stable-to-rising net interest income and stronger fee income as the mix driving earnings.
The pattern is not unique to Commerzbank. Financial sector earnings have been beating estimates across the board, with net interest income repeatedly surprising to the upside.
Why It Happened
The story is simpler than the headlines suggest. European banks are earnings machines in a higher-rate environment. Net interest income, the spread between what a lender charges borrowers and pays depositors, is the engine. When fee income is rising at the same time, the combination can overwhelm costs and drive operating leverage sharply higher.
At the same time, technology stocks led US equities lower as worries around the artificial intelligence trade mounted, pushing the Nasdaq 100 into correction territory, down more than 10% from its last peak in October. Capital rotating out of that trade has to go somewhere, and European financials have been a clear beneficiary.
What the Market May Be Missing
The profit beat masks one genuine soft patch: deposit competition. Commerzbank has already flagged that pressure can show up in net interest income assumptions as the cycle matures. That matters because it pushes the bank to lean harder on fee income and market-sensitive lines to sustain momentum, which is a different and more variable revenue mix.
The UniCredit backdrop adds a separate layer of complexity. In mid-October, UniCredit said it had received European Central Bank authorization to cross the 30% threshold in Commerzbank and to increase its stake further. UniCredit also said the remaining regulatory processes and conditions were expected around year-end, by when it would have approximately 50% of Commerzbank’s voting rights and be able to take control. Earlier in 2026, Reuters reported Commerzbank CEO Bettina Orlopp said she was convinced a tie-up with UniCredit could create value for both sides. These results are therefore partly a late-cycle performance for standalone Commerzbank: a demonstration that the bank was worth fighting over.
Where It Shows Up
European bank equities have been one of the cleanest expressions of the rotation. The Stoxx 600 Banks index is the clearest vehicle for this theme. Deutsche Bank, BNP Paribas, and Santander share the same structural tailwind: wider spreads, recovering fee income, and valuations that remain well below US financial peers. STOXX has said the EURO STOXX Banks index has traded around 1.2 times book value, about half the price of the EURO STOXX 50, and at roughly 10 times trailing earnings versus 18 for the benchmark. That discount has not fully closed despite the sector’s run.
Risks and Counterpoints
The bull case for European banks rests heavily on rates staying elevated long enough to sustain net interest income. But a sharper-than-expected economic slowdown in Germany could lift loan loss provisions and reverse today’s favorable operating leverage. Commerzbank’s own warning about deposit competition is an early signal that the easy gains can fade even in a still-high-rate world.
The UniCredit integration risk is real too. Reuters has reported UniCredit CEO Andrea Orcel has said a full merger could be pushed back to 2029 or 2030. Execution drag and strategic uncertainty could weigh on the stock even as the underlying earnings hold up.
What to Watch Next
Commerzbank has reaffirmed longer-term targets, including a net return on tangible equity of about 21% by 2030 and a cost-income ratio of 43% by 2030. Whether UniCredit’s ownership accelerates or disrupts that path is the question that will define the stock over the next two years. For the broader European bank trade, the next ECB meeting and the trajectory of German deposit competition are the near-term tests. If net interest income holds and the rotation out of US tech continues, the sector has more room. If either reverses, today’s record-setting tone in Europe will look like the high-water mark.