Hey there, bargain hunter.
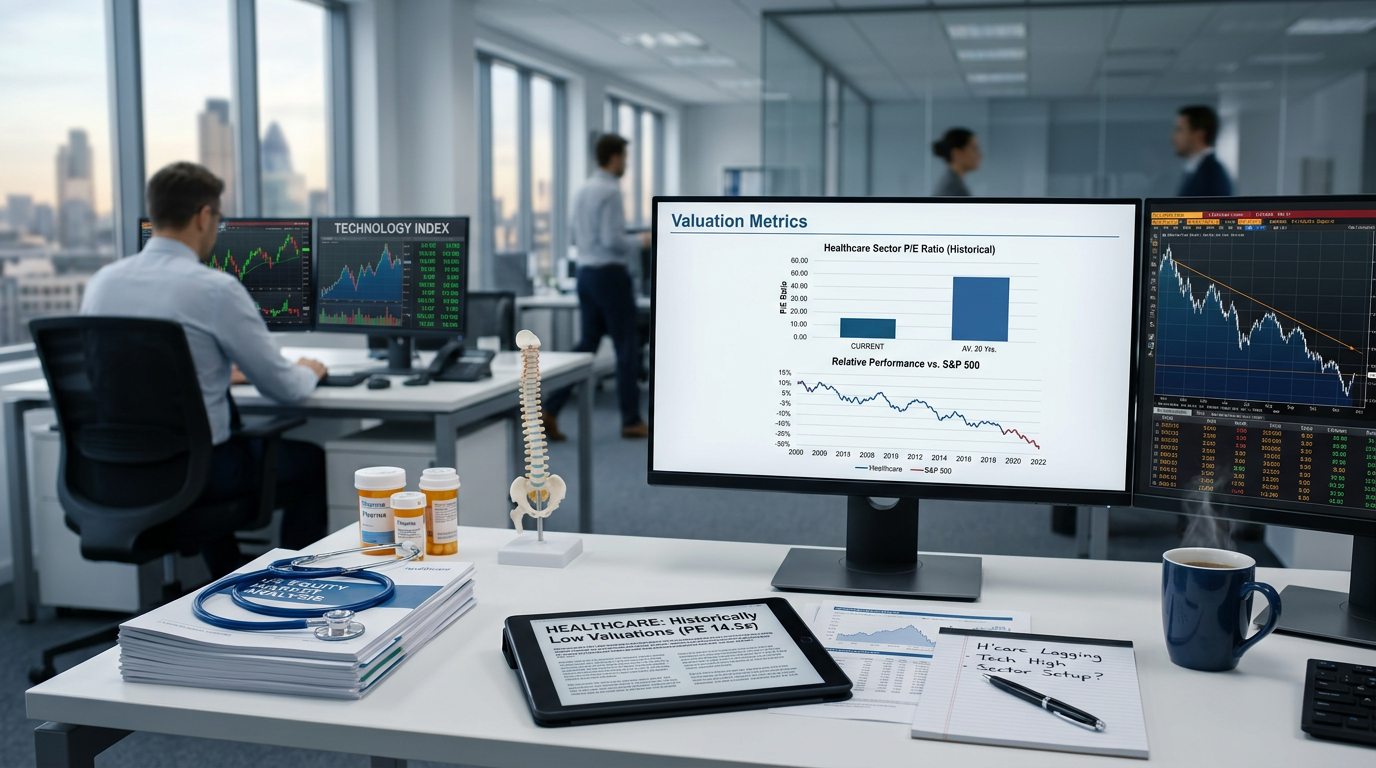
While everyone spent the last 18 months watching AI semiconductor stocks double and triple, something unusual was happening in healthcare. The sector got cheap. Not just cheaper than it was – cheap relative to its own 20-year history.
The Morningstar US Healthcare Index has fallen 4.44% year-to-date through May 2026, while the broader Morningstar US Market Index gained 7.62% over the same stretch. That’s a double-digit gap in a single year, stacked on top of years of underperformance. The result: healthcare now trades at roughly a 20% discount relative to the broader market.
That kind of valuation gap tends to mean revert. It doesn’t happen on a schedule, but it does happen.
Why It’s Cheap and Why That Might Be Changing
Policy overhang drove a lot of this. Drug pricing uncertainty, regulatory noise, and pandemic-era cost distortions hammered sentiment. But the setup is quietly improving. Supply chains have stabilized, staffing shortages have eased, and elective procedures are back to pre-pandemic volumes – meaning margins across much of the sector are rebuilding heading into the back half of 2026.
JPMorgan upgraded healthcare to a preferred sector citing three drivers: easing policy overhang, earnings clarity and stabilization, and accelerating M&A activity. The One Big Beautiful Bill Act now allows immediate expensing of R&D costs rather than multi-year amortization – a direct bottom-line benefit for pharmaceutical and biotech companies that’s still being priced in.
There’s also a structural AI story here that most people are skipping past. The rollout of generative AI is expected to shorten drug discovery timelines and lower development costs materially. That’s not a 2026 earnings event – but it’s the kind of long-duration setup that shows up in valuations before it shows up in revenue lines.
Where to Look
A few names worth watching for different reasons:
- Novo Nordisk (NVO): Down almost 8% in 2026 despite posting record revenue. GLP-1 competition from Eli Lilly is real, but Wegovy is now approved in pill form, label expansions into cardiovascular disease and chronic kidney disease are underway, and the company raised its semiannual dividend 37% to $1.04 per ADR – roughly a 3.9% yield at current prices.
- Bristol-Myers Squibb (BMY): Trading 17% below Morningstar’s fair value estimate of $70 per share with a wide economic moat rating. The pipeline is broad across oncology, cardiovascular, and immune disorders.
- Philips (PHG): Trading at a 36% discount to Morningstar’s fair value estimate of $41. Not a name most retail investors think about – which is often where the real opportunity lives.
- AbbVie (ABBV): Forward P/E of roughly 15.9x versus the healthcare sector average of 18.3x and the S&P 500’s 22.6x. Lost Humira exclusivity in 2023 and is rebuilding around newer immunology assets.
The part people skip: healthcare is defensive by nature. People don’t cancel prescriptions or delay critical procedures because the economy softens. The Centers for Medicare and Medicaid Services projects U.S. healthcare spending will grow 5.8% annually through 2033 – the demographic tailwind from an aging boomer population is not speculative. It’s already in the data.
The question isn’t whether healthcare recovers. It usually does when it gets this cheap. The question is whether you want to be positioned before the catalyst or after it.