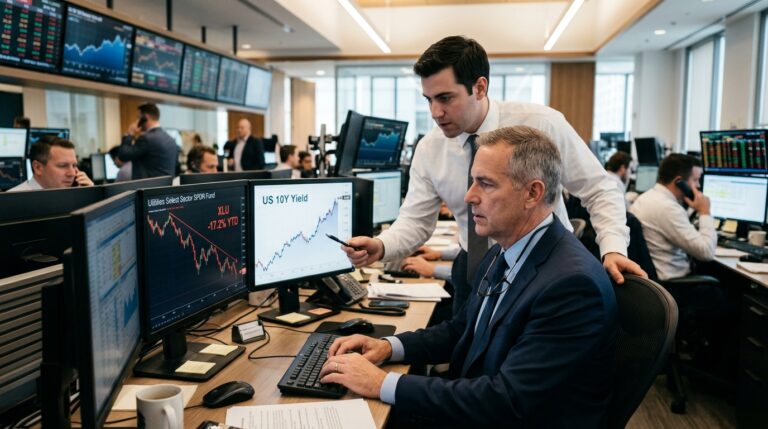
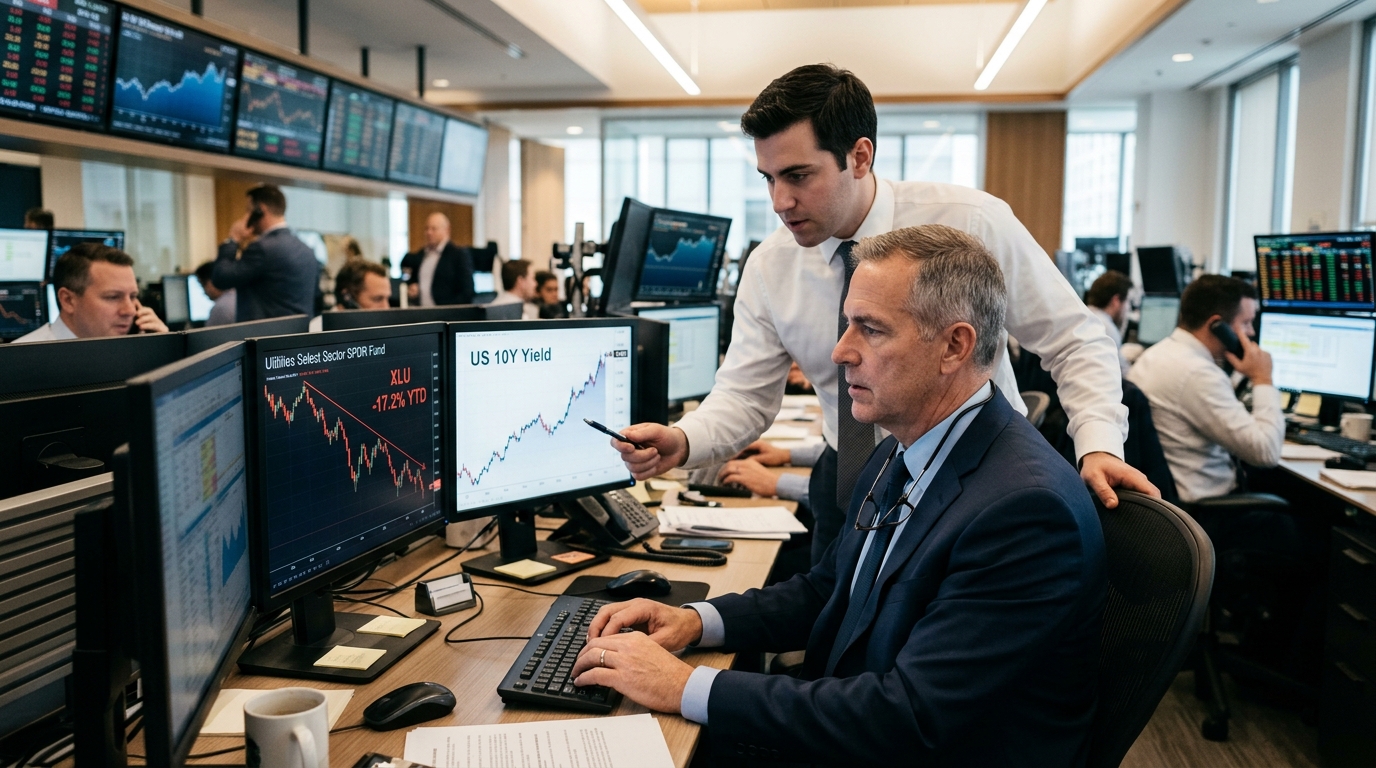
The utilities sector has become the bond market’s most visible casualty. XLU, the Utilities Select Sector SPDR ETF, has dropped about 7% over the past month and sits roughly 17% below its 52-week high of $47.80. The culprit is straightforward: the fastest rise in Treasury yields in decades has made the sector’s dividend yields structurally uncompetitive. The 10-year Treasury traded around 5.28% this week, up a little more than 1 percentage point from a year ago, while XLU yields roughly 3.05%. When risk-free paper pays that much more, income money migrates to bonds and utility prices fall until those yields close the gap.
That compression has been brutal and mechanical. The selloff has swept up the AI-power names alongside the regulated utilities: Constellation Energy (CEG), down sharply from its 2025 highs despite long-term nuclear power purchase agreements with Meta and Microsoft; Vistra (VST), carrying 20-year PPAs with Meta for about 2,600 MW of carbon-free power and capacity from its PJM nuclear fleet; and NextEra Energy (NEE), the fund’s largest holding at about 13% of XLU’s weight. None of the structural demand arguments for these companies has changed. The bond market simply overwhelmed every fundamental thesis.
Thursday changed the tone, at least on the margins.
About an hour after the opening bell on October 1, a string of options bets in XLU sent volume sharply higher versus recent norms, according to CBOE LiveVol and SpotGamma. The core position: a trader sold 5,000 of the January 39-strike puts and sold 5,000 of the January 42-strike calls, with XLU trading just above $39 at the time. The structure pays maximum if XLU settles between $39 and $42 by mid-January. This is not a bold directional bet on a utilities rally. It is a bet that the selling is finished. The trader is collecting premium by expressing confidence that the bottom is in, and that yields have stopped doing the damage they have inflicted all quarter.
The second trade is harder to dismiss. Later Thursday, in the rates complex at the CME, a buyer paid millions in premium for a large March 96/96.12 call spread on SOFR futures, with those contracts trading near 95.5 at the time. The position implies overnight rates fall back toward levels last seen earlier this summer. That is a rates call, not a utilities call, and it came on the same day the 10-year yield backed off an intra-day high around 5.34%.
Taken together, the XLU flow and the SOFR trade tell a specific story: at least two well-capitalized market participants placed meaningful, coordinated-feeling bets Thursday that the bond selloff is losing velocity. Options positioning in XLU also appeared less one-way than it was during last week’s peak fear.
The question for traders today is whether to join these positions or treat them as exhaustion signals being faded by the rest of the market. The case for joining: the 10-year has pulled back from its intraweek high above 5.34%, the Iran conflict remains the most obvious exogenous lever that could push oil and yields lower simultaneously, and XLU’s RSI sits near the mid-30s, oversold territory by many readings. The case against: a September jobs report hotter than the 84,000-job consensus estimate arriving Friday morning could resume the yield climb immediately, and XLU’s dividend yield still needs yields to retreat materially before income buyers return in size.
Watch $39 as the line in the sand. The January options structure is built around that level holding. A confirmed close below it invalidates the thesis the smart-money flow is pricing in. A bounce toward $41 with volume confirmation would validate it. CEG, VST, and NEE are the highest-beta expressions of the same trade for those who want individual-name exposure rather than the ETF wrapper.