Here is what’s interesting about Celestica right now. The stock has been one of the best-performing names in the entire S&P 500 over the past twelve months. Up more than 116%. And yet, heading into Q2 earnings today, the debate isn’t whether the company is growing. It’s whether it can keep growing fast enough to justify a valuation that leaves no room for a stumble.
That’s the only real question on the table.
Celestica (NYSE: CLS) reports Q2 2026 results after market close tomorrow, July 27. Wall Street is expecting revenue of roughly $4.35 billion and EPS of approximately $2.29 – which would represent about a 51% year-over-year revenue increase at the midpoint. That’s not a typo. Fifty-one percent.
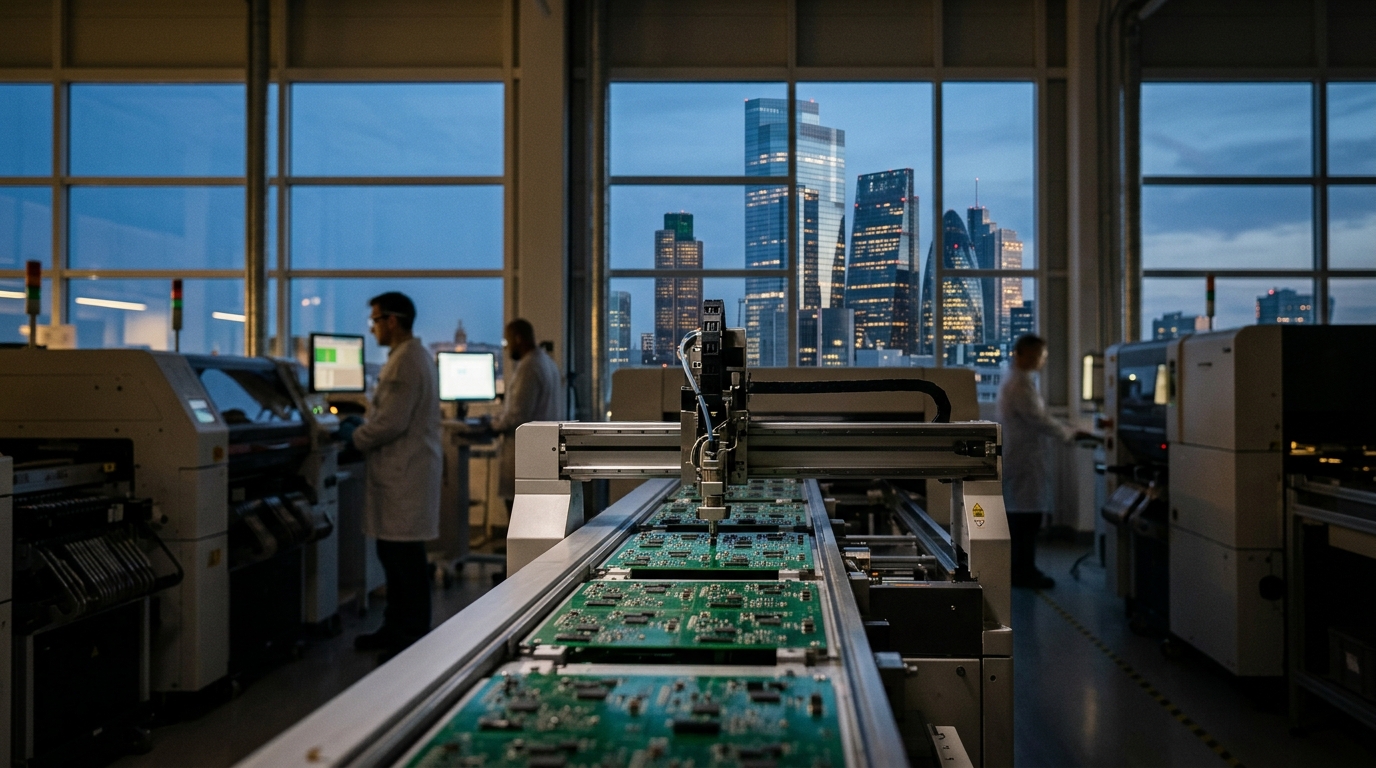
The business that once operated in the background of the tech world as a contract manufacturer has been quietly remaking itself into something much more valuable. Celestica is no longer just assembling hardware. It’s co-designing AI infrastructure.
What Changed
Think about where the AI hardware spending is actually going. Hyperscalers are pouring hundreds of billions into data center buildouts. GPUs get the headlines. But someone has to build the servers, the switches, the networking systems, and the storage platforms those GPUs live inside. That’s Celestica’s lane.
Q1 2026 was the clearest proof point yet. Revenue came in at $4.05 billion, up 53% year over year, landing within guidance. The Connectivity and Cloud Solutions segment – which includes AI cluster switches and hyperscaler infrastructure – grew 76% year over year and now represents roughly 80% of total company revenue. Enterprise division revenue was up 101% year over year, powered by new AI networking programs and hyperscaler demand.
Management responded by raising its full-year 2026 revenue outlook from $17 billion to $19 billion, and adjusted EPS guidance climbed from $8.75 to $10.15 – a 68% increase year over year at the midpoint. That’s a software-company growth rate inside an electronics manufacturer.
The Part People Are Skipping
Celestica isn’t just riding a wave. It’s building infrastructure that ties it directly to its customers’ long-term AI roadmaps. It’s ramping 800G and 1.6T networking programs with data center customers. And it just announced a new manufacturing campus in Fort Worth, Texas – over one million square feet, expected to support next-generation AI data center infrastructure and create roughly 1,700 skilled jobs.
The Fort Worth expansion is a strategic bet, not a defensive move. It signals management believes the AI infrastructure cycle has years left, not quarters.
Slight tangent, but it matters. Most investors focus on the semiconductor names in the AI supply chain. NVIDIA, AMD, TSMC. But the electronics manufacturing services layer – the companies that actually build, integrate, and test the hardware at scale – has quietly become one of the most critical chokepoints in the entire AI buildout. And Celestica may be the best-positioned name in that layer right now.
The Data-Driven Case
Over the trailing four quarters, Celestica has delivered an average earnings surprise of about 8%. The company has beaten EPS expectations consistently, and analysts have been repeatedly forced to revise estimates higher. Adjusted operating margins are expected to reach 8.1% for full-year 2026 – a meaningful expansion that shows the revenue growth is flowing through to the bottom line.
The free cash flow target stands at $500 million for the year, maintained even after the $2 billion revenue guidance raise. That tells you something about the discipline here. Capital expenditure guidance of roughly $1 billion in 2026 reflects the investment cycle needed to support the AI programs ramping through 2027.
Analysts have responded. Consensus price targets have moved sharply higher throughout the year, with the analyst consensus sitting at a Strong Buy heading into today’s print.
What Carries Risk
The bear case isn’t complicated. Customer concentration is real. Three customers represented 10% or more of revenue in the most recent quarter, including one that represented 35%. If a major hyperscaler slows its AI infrastructure spending, or shifts even a portion of its workload to an internal solution, that shows up fast in Celestica’s numbers.
The Q1 earnings reaction was instructive. Despite a strong beat and a significant guidance raise, shares pulled back in the days following the report, as investors questioned whether growth was peaking and flagged concerns around supply constraints. The market rewarded the numbers and then sold the news anyway.
That pattern could repeat tomorrow if the revenue beat is narrow or guidance isn’t raised again.
Valuation is the other variable. CLS is trading at roughly 26.6x forward earnings – a premium to the industry average, but still well below its own historical mean of 37x. That’s an unusual setup. The stock is expensive versus peers and cheap versus itself.
The Bigger Picture
The hyperscaler AI spending cycle is nowhere near done. Meta, Alphabet, Microsoft, and Amazon have all reaffirmed massive capital expenditure commitments for 2026 and beyond. Every dollar they spend on AI infrastructure eventually flows through companies like Celestica that design, manufacture, and test the physical hardware.
The $19 billion revenue target for 2026 implies roughly 53% growth versus 2025’s $12.4 billion. If the company delivers on that, and tomorrow night’s Q2 results suggest the trajectory is intact, the valuation debate shifts meaningfully. And the $10.15 adjusted EPS guide for the full year gives investors a hard number to anchor against.
The real test isn’t whether Celestica is in the right business. It is. The question tomorrow is whether the revenue line holds above $4.35 billion and whether management raises guidance again. If both happen, the story gets louder. If either misses, expect the same violent re-rating the stock saw after Q1.
Keep watching the guidance commentary closely. That’s where this one gets decided.
Disclaimer: This editorial is for informational and educational purposes only. It does not constitute financial advice or a recommendation to buy or sell any security. All data and projections referenced are sourced from publicly available information and analyst estimates. Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results.