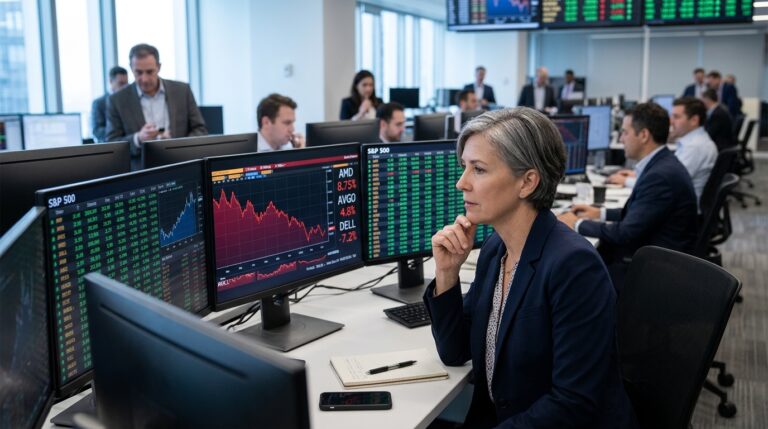
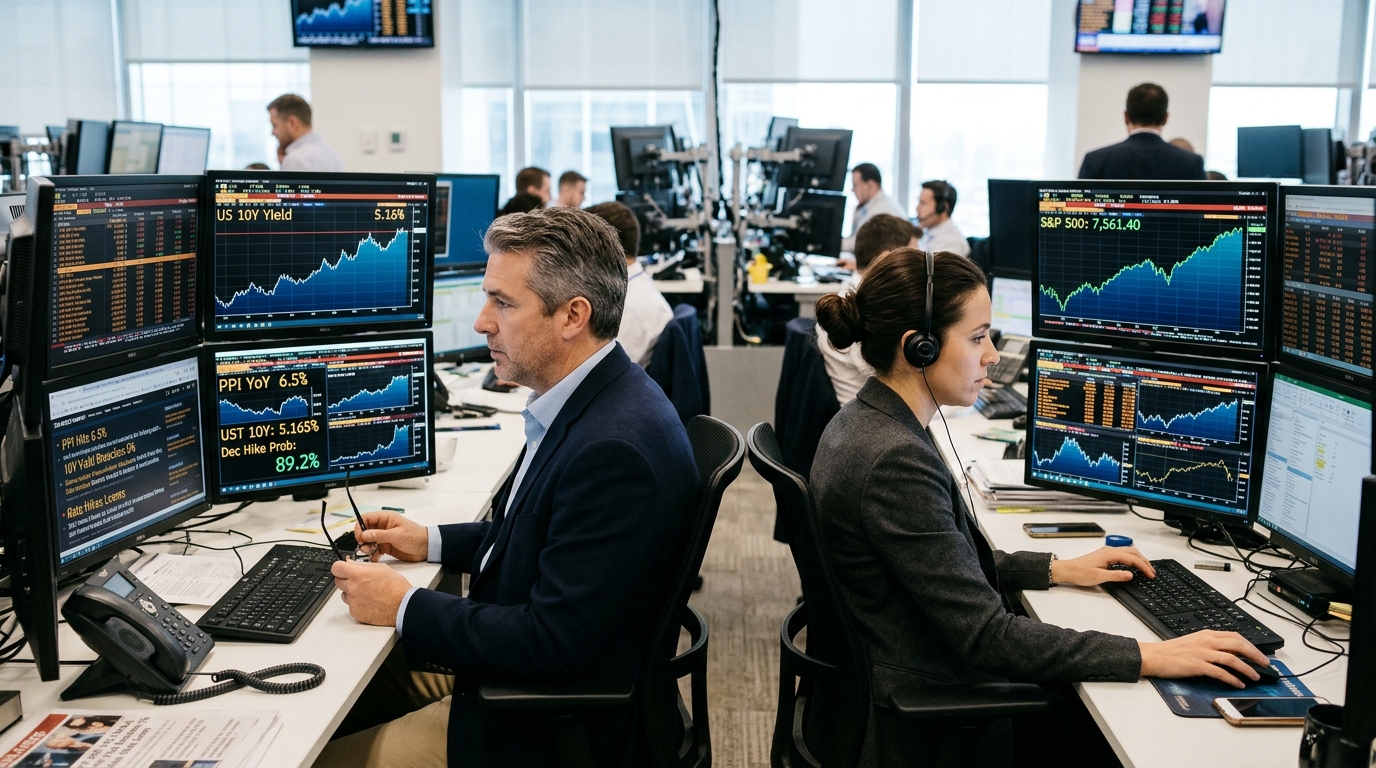
The bond market delivered its verdict Friday morning and it was not ambiguous. The 10-year Treasury yield touched 5.174% intraday before settling around 5.15%, adding to Thursday’s surge that pushed the benchmark back above 5% for the first time in weeks. The proximate cause was the October Producer Price Index, which landed at 6.5% year over year, the largest 12-month increase since November 2022, up from 6.3% in September. That number is not the bond market’s problem. The S&P 500 at 7,561 is.
What the numbers actually said
The monthly figure came in at +0.3%, a tenth below the 0.4% consensus, which gave equity bulls a brief opening at the bell. The S&P opened higher, briefly touched 7,621.78, then slid to an intraday low of 7,499.40. It recovered to close at 7,561.67, down 0.40% on the day, though still up 2.5% for the week after snapping a four-week losing streak.
The monthly softness deserves context. September’s reading held at 1.4%, the hottest monthly jump of the year. October’s moderation was largely energy-driven: food prices rose 1.3% while energy slipped 0.1% after a sharp surge the prior month. Strip those swings out and prices for final demand less foods, energy, and trade services rose 0.5% in October, the same as in September. On a 12-month basis, that measure ran at 4.9%. The pipeline is not clearing.
What the rates market concluded
Futures markets continued to lean toward a quarter-point move in December, with odds around 90% late Friday. The larger half-point scenario has remained a live debate since Fed Governor Christopher Waller said earlier this month he would consider the larger increment if core CPI came in around 0.3% or higher. It did. The market’s response was to keep the base case anchored to 25 basis points, reading the combination of elevated inflation and incremental month-to-month cooling as enough cover for the committee to stay deliberate.
Goldman Sachs went further. After a third consecutive upside inflation surprise, the bank added a March 2027 hike to its forecast alongside December, now seeing the federal funds rate peak at 4.25% to 4.50%, with the first cut pushed back to December 2027. The Fed currently sits at 3.75% to 4.00%, where it held at the October 28 meeting despite two dissents in favor of an immediate increase.
The rate path Goldman now projects depends on how much further yields can move before equity valuations crack. Each additional quarter-point in the 10-year yield compresses equity multiples through a distinct set of sector and duration channels.
Where equities and bonds diverge
Here is the gap worth watching. The S&P 500 is still up roughly 10% over the past year, trading at a level that implies a relatively benign earnings and discount-rate outlook. The 10-year yield near 5.15% tells a different story about the cost of capital. That spread between equity valuations and Treasury yields has periodically resolved itself through equity weakness rather than yield declines, and Friday’s intraday reversal from the open high offered a small preview of that tension.
The week ahead will test whether the gap narrows. Fed Chair Kevin Warsh speaks Monday in San Francisco at the Fed’s Productivity and Jobs Task Force Conference. New York Fed President John Williams is also scheduled to speak Wednesday at 9:05 a.m. ET. Wednesday brings the October FOMC minutes, which will show whether the two dissenting hawks at the October meeting represent a broader lean on the committee. As Newsquawk noted, those minutes tend to matter most when they reveal internal dispersion on the rate path rather than simply restating the decision.
Warsh’s independence from political pressure is itself a market variable. Bond investors have already priced the gap between White House rate-cut demands and Warsh’s publicly hawkish inflation stance.
What to watch
Warsh’s Monday remarks are the first scheduled signal from the chair since the PPI landed. Any language that acknowledges the annual rate’s persistence without endorsing the half-point scenario would confirm the market’s current quarter-point read. Any hint of impatience, particularly around the stubborn underlying pace implied by the October data, could quickly reopen that larger-move debate. The minutes on Wednesday will show whether the October dissenters were outliers or a leading indicator of where the full committee is heading into December 9.